

Railway Signalling System Market (2025-2034)
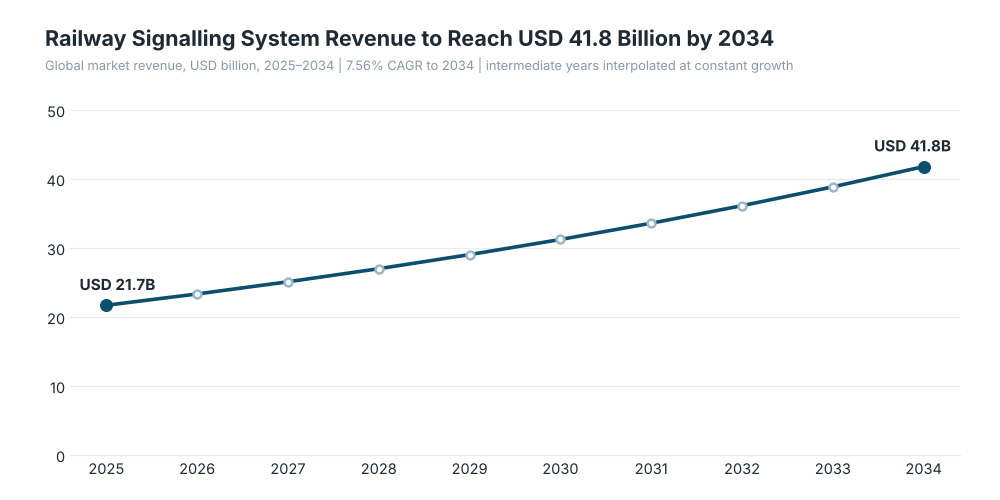
The Global Railway Signalling System Market is estimated at USD 21.7 billion in 2025 and is projected to reach USD 41.8 billion by 2034, expanding at a CAGR of 7.56% during the forecast 2034.



Quick Enquiry
How Large Is the Railway Signalling System Market and What Is Fueling Its Expansion?
The Global Railway Signalling System Market is estimated at USD 21.7 billion in 2025 and is projected to reach USD 41.8 billion by 2034, expanding at a CAGR of 7.56% during the forecast period. This estimate is positioned between recent published market assessments that place 2025 values broadly around USD 19–24 billion, while their longer-term forecasts point to continued high-single-digit expansion.
Railway signalling systems coordinate train movement, enforce separation, prevent collisions and increasingly manage capacity through automated train control. Demand is rising as operators modernize ageing networks rather than simply add new track. ETCS remains central to European interoperability, while PTC in North America and Kavach in India reflect country-specific safety architectures. In Europe, ETCS deployment across Core Network Corridors was only 15% by 2024, leaving a substantial modernization pipeline.
Urban rail is adding another demand engine. CBTC can bring train headways to 90 seconds or less, turning signalling into a capacity investment rather than only a safety expense. The addressable onboard market is also expanding as nearly 19,600 railway vehicles received European safety authorizations in 2024, while India earmarked ₹1,112.57 crore for Kavach deployment.
Key Report Takeaways: Railway Signalling System Market
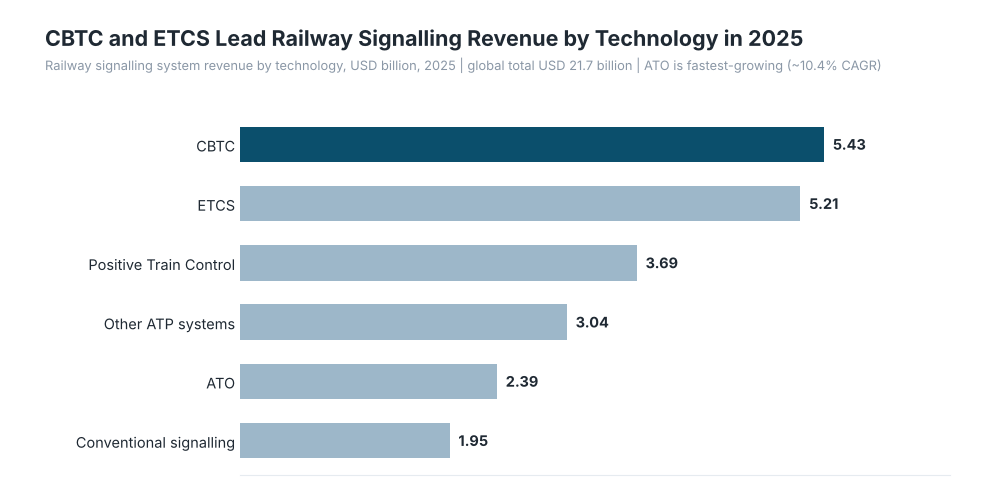
- Within railway signalling technologies, CBTC is estimated to remain the dominant subsegment with a 25.0% market share and USD 5.43 billion in 2025, while ATO is projected to be the fastest-growing, advancing at a 10.4% CAGR from an estimated 11.0% share.
- For application environment, outside-station signalling accounts for an estimated 79.0% share, equivalent to USD 17.14 billion in 2025, whereas inside-station systems are expected to expand faster at a 9.1% CAGR as increasingly automated stations require tighter platform, routing and train-management coordination.
- Trackside infrastructure leads the system-layer segmentation at approximately 38.0% share and USD 8.25 billion in 2025, with onboard signalling units emerging as the fastest-growing layer at a 9.9% CAGR and an estimated 29.0% share.
- In rail-type deployment, mainline signalling represents the largest opportunity at around 43.0% of the market, while urban metro signalling is forecast to record the strongest growth at a 9.4% CAGR as operators seek shorter headways and higher passenger throughput.
- Mainline and freight networks continue to generate sizeable replacement demand because interlocking, train protection and detection assets must remain compatible with increasingly digital control architectures.
- Onboard equipment and lifecycle services are gaining importance as signalling moves from one-time hardware installation toward software, diagnostics, communications and recurring maintenance.
Regulations and Standards Shaping the Railway Signalling System Market
The railway signalling system market is unusually dependent on mandatory safety and interoperability frameworks. In the European Union, Commission Implementing Regulation (EU) 2023/1695 establishes the Control-Command and Signalling Technical Specification for Interoperability and covers trackside and onboard CCS systems, train protection, railway radio communications, train detection and automated train operation. The framework also embeds ETCS and provides the regulatory basis for migration toward ERTMS and newer railway communications.
The U.S. market is shaped by 49 CFR Part 236 and the Positive Train Control framework established under federal rail-safety legislation. PTC requirements create recurring demand for certified train-control equipment, validation, inspection, maintenance and software support across covered passenger and freight routes.
India has developed its own regulatory pathway through RDSO's Kavach specification, with Version 4.0 formally approved in July 2024 for higher-speed protection requirements. Urban transit systems are additionally influenced by IEC 62290, which defines functional, system and interface requirements for urban guided transport management and command/control systems.
Market Analysis Narrative: Railway Signalling System Market
CBTC remains the largest technology category, accounting for an estimated 25.0% share or USD 5.43 billion in 2025, with a projected 8.7% CAGR through 2034. Demand is rising because metro operators can increase frequency without undertaking equally expensive civil expansion. For example, Alstom's Urbalis platform is being deployed across metro modernization projects, while Siemens is moving CBTC toward cloud-ready architectures through its Signaling X platform. These developments show the shift from fixed signalling equipment toward software-led capacity management.
ETCS is estimated at 24.0% of the technology market, representing USD 5.21 billion in 2025, and is expected to grow at an 8.2% CAGR. The demand case is strongest where networks must replace national train-control systems with interoperable European technology. For example, Siemens Mobility and Sonda are delivering ETCS Level 1 technology for Mexico's Mexico City–Querétaro–Irapuato corridor, extending the system beyond its traditional European base. Stadler also maintains a signalling portfolio spanning onboard and wayside ETCS, particularly for retrofit opportunities.
Positive Train Control represents an estimated 17.0% share and USD 3.69 billion in 2025, with growth of about 5.8% CAGR. Its expansion is slower than CBTC or ETCS because the U.S. market has already moved through the principal statutory deployment cycle, but the installed base supports continuing demand for upgrades, software and lifecycle support. For example, Wabtec's signalling and systems business covers PTC alongside conventional signalling, CBTC, communications and back-office integration, keeping the company positioned in the replacement and maintenance phase of North American deployment.
Other automatic train protection systems account for approximately 14.0% of technology demand, equivalent to USD 3.04 billion in 2025, and are projected to grow at a 6.5% CAGR. These systems remain relevant where national signalling architectures cannot yet transition fully to ETCS or other standardized platforms. Suppliers continue to adapt safety technology to legacy infrastructure, keeping this category commercially relevant across conventional networks.
ATO represents roughly 11.0% of the technology market and USD 2.39 billion in 2025, but it is expected to expand at the fastest technology CAGR of about 10.4%. Its momentum comes from metro automation, unattended train operation and tighter integration between train control and operations management. Mitsubishi Electric's radio-based train control portfolio, for instance, combines train positioning, wayside control and onboard control functions to support increasingly automated railway operations.
Conventional signalling systems account for the remaining estimated 9.0%, or USD 1.95 billion in 2025, and should grow at around 4.0% CAGR. The category is not disappearing. Many operators still need relay replacement, axle counting, track circuits, signals and electronic interlocking upgrades before a full digital migration becomes commercially practical. Indian specialists such as Bharat Rail Automation and Efftronics continue to serve this modernization layer through interlocking, train detection and connected signalling solutions.
Outside-station applications dominate the application environment with an estimated 79.0% share, worth USD 17.14 billion in 2025, and are projected to expand at a 7.1% CAGR. This category includes the equipment controlling trains across open route sections, junctions and corridors, making it the core expenditure area for network modernization. For example, CAF's signalling work with ADIF covers conventional, metric and high-speed railway networks, while MERMEC provides ETCS, computer-based interlocking, traffic control and lineside equipment. The breadth of these portfolios reflects the continuing demand for network-wide modernization rather than isolated station upgrades.
Inside-station applications hold an estimated 21.0% share, equal to USD 4.56 billion in 2025, but should grow faster at approximately 9.1% CAGR. Automated routing, platform operations, passenger-flow management and higher-frequency metro services are increasing the complexity of station signalling. Demand is particularly strong where terminals and interchange stations become capacity bottlenecks, forcing operators to extract more movements from existing infrastructure.
Trackside signalling represents the largest system-layer category at an estimated 38.0% share and USD 8.25 billion in 2025, growing at roughly 6.5% CAGR. Signals, interlockings, train detection, balises, level-crossing interfaces and wayside controllers remain essential, even as architectures become more software driven. Knorr-Bremse, for example, maintains a broad CCS portfolio covering railway safety technology, signalling and associated infrastructure, while Indra's digital signalling architecture connects interlocking with ETCS and IoT capabilities.
Onboard signalling is estimated at 29.0% share and USD 6.29 billion in 2025 and is projected to expand at a 9.9% CAGR. Demand is being pulled by fleet retrofits, new interoperable rolling stock and the need for trains to operate across networks using different protection regimes. The European authorization activity described in the supplied evidence is particularly important because every newly authorized cross-border vehicle expands the pool requiring compliant onboard control equipment. Stadler, Hitachi Rail and specialist suppliers such as MERMEC are positioned across this onboard retrofit and new-build opportunity.
Control-center systems account for an estimated 18.0% share, or USD 3.91 billion in 2025, with an expected 7.8% CAGR. Traffic management is becoming more software intensive as operators seek centralized supervision and better timetable optimization. Siemens, for instance, is integrating interlocking and signalling functions into centralized data-center architectures, while Indra combines traffic control with digital interlocking and railway IoT.
Telecommunications and signalling services represent approximately 15.0% of the system-layer market, or USD 3.26 billion in 2025, and should grow at a 9.6% CAGR. The migration from GSM-R toward FRMCS is strengthening the role of communications in train control, automation and predictive maintenance. Nokia's FRMCS portfolio connects railway networks through 5G radio, core and transport infrastructure, positioning communications as a foundational part of future signalling architectures rather than a separate support layer.
Mainline rail remains the largest rail-type category, with an estimated 43.0% share and USD 9.33 billion in 2025, growing at approximately 7.1% CAGR. Its demand profile is strongly tied to safety mandates, interoperability and replacement of ageing control infrastructure. Europe illustrates the scale of the opportunity particularly clearly: only 15% of ETCS deployment on Core Network Corridors had been achieved by 2024, leaving considerable modernization work ahead. Firms such as Alstom, Siemens Mobility and Hitachi Rail remain deeply positioned in this long-cycle market.
Urban metro signalling accounts for roughly 28.0% of the market and USD 6.08 billion in 2025, but its 9.4% CAGR makes it the fastest-growing major rail-type application. Operators are buying signalling to increase passenger throughput, automate services and reduce waiting times. For example, Alstom's current Lausanne m2 modernization combines new CBTC with fleet modernization, while its Indore deployment applies Urbalis Forward to support higher-frequency metro operations. These projects show that urban signalling demand is increasingly linked directly to capacity expansion.
Freight rail represents an estimated 17.0% share, or USD 3.69 billion in 2025, with growth of roughly 6.0% CAGR. Freight operators place greater emphasis on reliable train protection, long-distance control and integration with existing dispatching systems. North America's mature PTC base provides a particularly durable services opportunity, with the supplied evidence identifying approximately 5,000 BNSF locomotives as part of the installed PTC footprint.
High-speed rail contributes approximately 12.0% of the market, equivalent to USD 2.60 billion in 2025, and should expand at around 8.7% CAGR. Safety requirements become more demanding as speed rises, making train protection, reliable communications and advanced traffic supervision essential. Demand is also supported by new high-speed corridors and modernization of existing routes, particularly in Europe and Asia.
Regional Analysis: Railway Signalling System Market
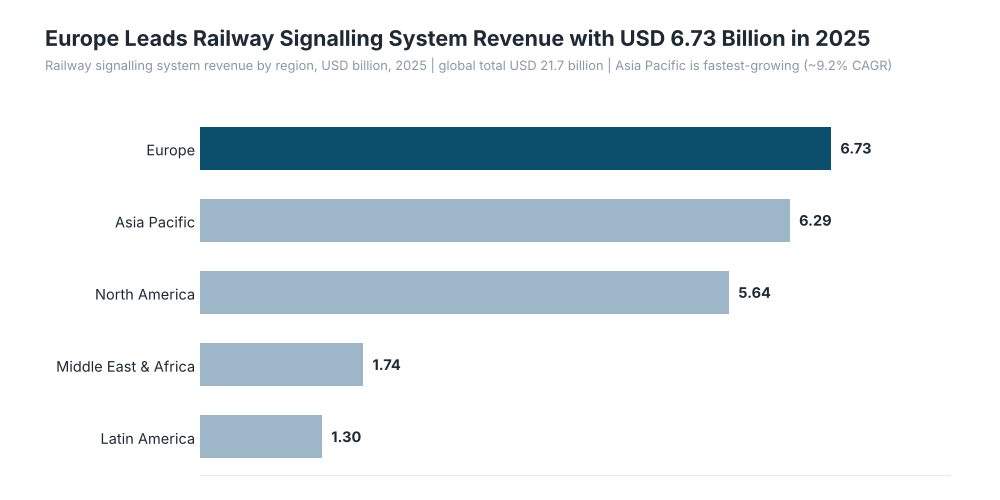
Europe is estimated to hold the largest regional share at approximately 31.0%, representing USD 6.73 billion in 2025, with a projected 7.1% CAGR. Its demand is heavily supported by interoperability mandates, ETCS rollout and replacement of fragmented national signalling systems. The relatively low ETCS penetration across European Core Network Corridors leaves a sizeable retrofit pipeline, even though procurement schedules remain constrained by funding and regulatory complexity. Alstom, Siemens Mobility, Hitachi Rail and Stadler are positioned across this migration cycle. For example, Alstom is combining CBTC modernization with lifecycle services in European metro networks, while Siemens continues to secure ETCS projects as European signalling architectures increasingly extend into adjacent markets.
Asia Pacific accounts for an estimated 29.0% share, or USD 6.29 billion in 2025, and is expected to grow at the fastest regional CAGR of about 9.2%. Expansion of metros, high-speed rail, freight corridors and national safety programmes is driving demand. India is particularly significant because domestic signalling requirements are supporting a growing supplier ecosystem around Kavach, electronic interlocking and digital train control. For example, Alstom is deploying Urbalis Forward on Indian metro infrastructure, while HBL Engineering has developed and received approval for Kavach Version 4.0 equipment. Siemens' cloud-ready CBTC demonstrations in Singapore also indicate that Asia is becoming a test bed for next-generation signalling architectures.
North America represents an estimated 26.0% share, amounting to USD 5.64 billion in 2025, with growth of about 5.7% CAGR. The market is comparatively mature, but PTC has created a substantial installed base requiring cybersecurity updates, software maintenance, system integration and lifecycle replacement. Wabtec remains a major supplier across signalling, PTC and train-control integration, allowing demand to migrate from first-time installation toward long-term support and network modernization.
The Middle East and Africa region is estimated to account for 8.0% of the market, equivalent to USD 1.74 billion in 2025, and is projected to grow at an 8.1% CAGR. New metro systems, intercity rail investment and modernization of strategic corridors are generating demand for turnkey signalling, centralized traffic control and communications infrastructure. Adoption is generally project-led, with suppliers competing on system integration capability and the ability to combine signalling, telecommunications and operations control.
Latin America holds an estimated 6.0% share, or USD 1.30 billion in 2025, and is forecast to expand at approximately 8.4% CAGR. The region remains smaller in absolute terms but has a growing modernization pipeline as governments revive passenger rail and upgrade existing networks. For example, Siemens Mobility's ETCS project for the Mexico City–Querétaro–Irapuato corridor extends advanced train-control technology into a new national rail corridor while also integrating traffic planning and control-center functions.
Competition Landscape: Railway Signalling System Market
The competitive structure is concentrated at the top but increasingly fragmented below the largest system integrators. Alstom, Siemens Mobility, Hitachi Rail, Wabtec, Knorr-Bremse, Stadler and CAF operate across multiple signalling layers, while specialist firms compete in onboard protection, interlocking, train detection, communications, testing and digital asset management. Hitachi's acquisition of Thales Ground Transportation Systems materially strengthened its installed base and signalling capability, while the supplied industry evidence also points to a broader shift toward software and recurring lifecycle services.
Alstom's portfolio spans ETCS/ERTMS, CBTC, interlocking, automatic train operation, onboard control, traffic management, cybersecurity and lifecycle services. Siemens Mobility competes across ETCS, CBTC, interlocking, control centers, communications and digital signalling, including its Signaling X architecture. Hitachi Rail combines ETCS, CBTC, interlocking, traffic management, digital asset management and related services following the integration of Thales GTS. Wabtec focuses strongly on PTC, conventional signalling, CBTC, train control, communications and back-office systems in North America. Knorr-Bremse adds signalling, control-command and safety systems alongside its broader rail vehicle portfolio, while Stadler covers ETCS retrofits, onboard and wayside signalling, branch-line automation and CBTC metro systems.
The specialist field is also important. CAF is strengthening its own signalling capability through CBTC and national network signalling contracts. Mitsubishi Electric supplies radio-based train control, CBTC and onboard and wayside equipment, while Kyosan Electric competes in CBTC and ATC systems. Nippon Signal, MERMEC and Indra cover signalling, train protection, interlocking, traffic control and infrastructure technologies. Nokia and Huawei participate more heavily at the railway communications layer, particularly as FRMCS and private wireless networks become more important to digital signalling.
The smaller-company and emerging innovation layer is broader than the traditional OEM landscape. Indian participants include HBL Engineering, RailTel, Efftronics, Bharat Rail Automation, Deltron, Cosmic Signaling, Eldyne and Insys Digital Systems, with capabilities ranging from Kavach and electronic interlocking to axle counters, smart signalling and EPC integration. International specialist and startup activity includes Prover, Cactus Rail, GEAR International Holdings, Humatics, TekTracking, Fidrox and STraffic, particularly around formal verification, train localization and digital signalling. Prover's technology, for example, supports formal development and verification of signalling application software against CENELEC SIL 4 requirements, illustrating where specialist software suppliers can capture value without competing directly with Tier-1 system integrators.