

Green Steel Market (2026-2034)
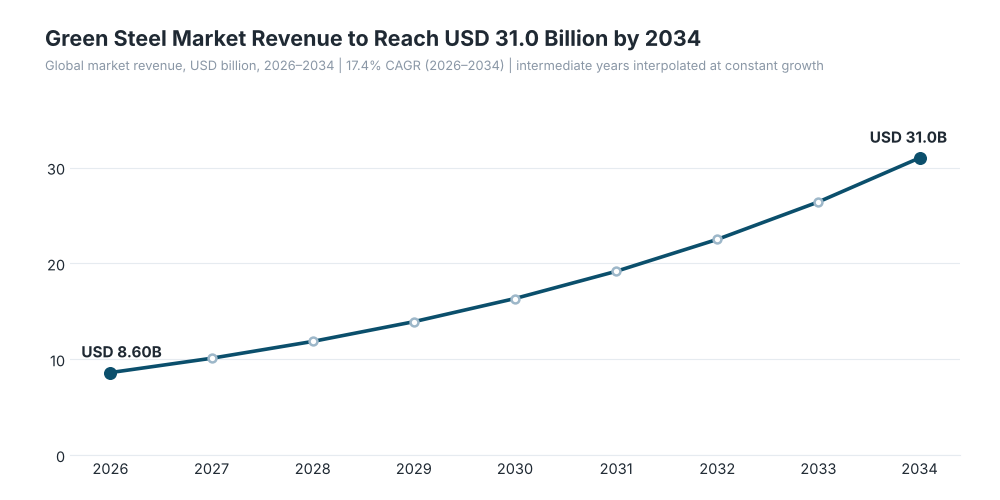
The Global Green Steel Market is analytically estimated at USD 8.60 billion in 2026 and is expected to reach USD 31.00 billion by 2034, expanding at a CAGR of 17.4%.



Quick Enquiry
How Large Is the Opportunity in the Green Steel Market and What Is Driving Adoption?
The Global Green Steel Market is analytically estimated at USD 8.60 billion in 2026 and is expected to reach USD 31.00 billion by 2034, expanding at a CAGR of 17.4%. Green steel refers to steel produced with materially lower greenhouse-gas emissions than conventional blast-furnace steel, using routes such as renewable-powered electric arc furnaces, hydrogen-based direct reduction and other lower-carbon processes. Demand is moving from pilot procurement toward contracted supply as manufacturers seek to lower Scope 3 emissions and protect exports from carbon regulation. The First Movers Coalition requires participating steel buyers to make at least 10% of annual steel purchases near-zero emissions by 2030, with the benchmark reaching 50–400 kg CO2e per tonne depending on scrap content. Automotive, construction, industrial machinery, infrastructure and energy equipment are the main applications. The commercial opportunity is widening because steelmakers are securing offtake before commissioning new capacity, while the EU CBAM has entered its definitive regime from 1 January 2026, making embedded carbon a direct commercial consideration for imported steel.
Key Report Takeaways
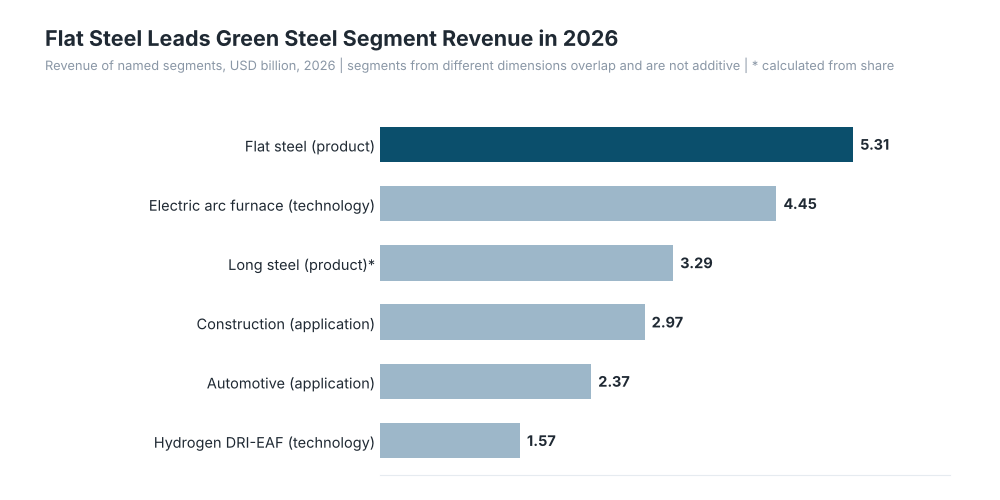
- In production technology, electric arc furnace steel is estimated to remain the dominant route with a 51.8% share worth about USD 4.45 billion in 2026, while hydrogen DRI-EAF is the fastest-growing pathway at a 24.6% CAGR and an estimated 18.2% share worth USD 1.57 billion.
- Construction remains the largest end-use segment at an estimated 34.5% share and USD 2.97 billion in 2026, whereas automotive is advancing fastest at a 22.8% CAGR with approximately 27.6% share and USD 2.37 billion in value.
- Flat steel accounts for the larger product base at an estimated 61.7% share, equivalent to USD 5.31 billion in 2026, while long steel is expected to register the stronger growth rate of about 19.1% CAGR from a 38.3% share.
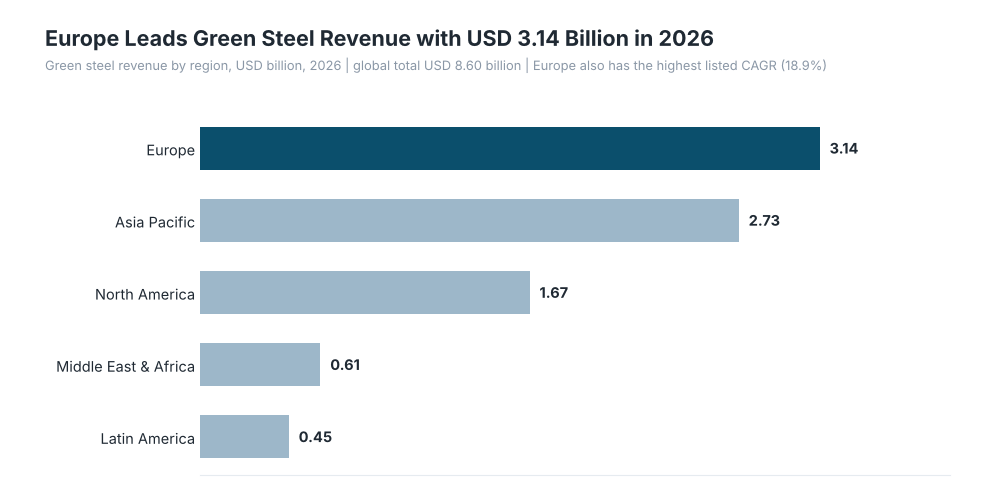
- Europe leads regional demand at an estimated 36.5% share, or USD 3.14 billion in 2026, supported by CBAM, industrial decarbonization programs and early green-steel procurement, while Asia Pacific follows with a 31.8% share worth approximately USD 2.73 billion.
- North America represents an estimated 19.4% of 2026 demand, with growth increasingly tied to domestic low-carbon steel programs, renewable electricity availability and procurement by automotive and infrastructure customers.
How Regulations and Standards Are Rewriting the Green Steel Market
Regulation is turning low-carbon steel from a sustainability preference into a procurement and trade issue. In the European Union, the Carbon Border Adjustment Mechanism entered its definitive regime on 1 January 2026. Importers of covered goods must account for embedded emissions and ultimately surrender CBAM certificates, increasing the economic penalty attached to carbon-intensive steel supplied into the EU. The First Movers Coalition applies a much tighter commercial benchmark, defining near-zero steel at roughly 50–400 kg CO2e per tonne depending on scrap input and requiring participating buyers to target at least 10% near-zero steel procurement by 2030. SteelZero uses a broader pathway, targeting 50% low-emission steel procurement by 2030 and 100% net-zero steel by 2050. India has also established a national Green Steel Taxonomy, notified in December 2024, using a threshold of below 2.2 tonnes of CO2e per tonne of finished steel and assigning star ratings according to emissions intensity. The framework is intended to support certification and market development. These rules increasingly influence supplier selection, export economics, product declarations and long-term offtake contracts.
How Production Technology Is Reshaping the Green Steel Market
Electric arc furnace technology is estimated to hold a 51.8% share of the Green Steel Market in 2026, generating about USD 4.45 billion, because EAFs can cut emissions rapidly where scrap and renewable electricity are available. The route is especially attractive for construction steel, reinforcing products and other applications where existing furnaces can be upgraded without fully rebuilding integrated steelworks. ArcelorMittal already markets XCarb recycled and renewably produced steel from EAFs using high scrap content and renewable electricity, while Nucor offers its Econiq portfolio across steel and fabricated products. The constraint is not the furnace itself. Scrap quality, electricity cost and renewable-power availability determine how low the final footprint can fall.
Hydrogen DRI-EAF is the fastest-growing production pathway, expanding at an estimated 24.6% CAGR and representing about 18.2% of 2026 market value, or USD 1.57 billion. The technology is gaining traction because it addresses primary ironmaking, where scrap-based EAFs cannot solve the entire emissions problem. For example, Stegra has built its commercial model around hydrogen-based direct reduction, while SSAB, through HYBRIT, is developing fossil-free iron and steel using hydrogen and fossil-free electricity. The IEA notes, however, that early commercial H2 DRI-EAF plants can still cost materially more than conventional BF-BOF facilities, keeping financing and renewable-energy access central to project economics.
Which Applications Are Pulling the Green Steel Market Forward?
Construction remains the dominant end-use application with an estimated 34.5% share and USD 2.97 billion in 2026, mainly because structural steel, rebar, profiles and other high-volume products represent a large addressable base for lower-carbon procurement. Yet demand is still price sensitive, particularly where project developers cannot recover higher material costs. Government procurement can change that equation; government-funded construction and infrastructure represented about 27% of total steel demand in India in 2019, creating a meaningful route for low-carbon standards to influence future purchasing.
Automotive is the fastest-growing application at an estimated 22.8% CAGR, with a 27.6% share worth around USD 2.37 billion in 2026. Automakers are moving beyond statements and into supply contracts because steel is a measurable part of upstream Scope 3 emissions and can be integrated into existing vehicle platforms. For example, Mercedes-Benz has signed a binding agreement with H2 Green Steel for around 50,000 tonnes of almost CO2-free steel annually, while Nissan has adopted Nippon Steel’s NSCarbolex Neutral for mass-produced vehicles. This makes automotive one of the clearest early markets where premium steel can be tied to product-level decarbonization rather than sold purely on environmental credentials.
How Steel Product Mix Is Changing the Green Steel Market
Flat steel commands an estimated 61.7% share of the 2026 Green Steel Market, equal to roughly USD 5.31 billion, supported by automotive body panels, appliances, machinery, energy equipment and other applications that rely heavily on high-grade sheet and coil. Buyers in these markets are more willing to specify low-carbon grades when emissions data can be attached to existing product quality. Thyssenkrupp Steel’s bluemint range, for instance, provides reduced-CO2 flat steel across established grades, while voestalpine offers CO2-reduced greentec steel editions across flat steel products without changing their application properties.
Long steel is estimated to account for 38.3% of market value in 2026 and is projected to grow at about 19.1% CAGR, faster than the overall product mix as infrastructure, renewable-energy projects and heavy construction increasingly demand lower-carbon beams, sections and reinforcement products. Early adoption includes structural and machinery applications where recycled-feedstock EAF production is commercially practical. Companies such as Salzgitter and SSAB are expanding their low-carbon offers into construction and industrial applications, with SALCOS positioned around hydrogen-based steelmaking and SSAB developing fossil-free steel for equipment and infrastructure uses.
Europe Is Setting the Commercial Pace for the Green Steel Market
Europe is estimated to command 36.5% of global Green Steel Market value in 2026, equivalent to about USD 3.14 billion, with an estimated 18.9% CAGR through 2034. Demand is rising faster because regulation and industrial procurement are working together. CBAM increases the commercial exposure of carbon-intensive imports, while European buyers are signing advance agreements to secure low-carbon material. For example, Mercedes-Benz is contracting near-zero steel supply while ArcelorMittal is expanding its XCarb portfolio across flat and long products; these moves demonstrate that European demand is increasingly being converted into defined material specifications rather than broad sustainability objectives.
Asia Pacific represents an estimated 31.8% share, or USD 2.73 billion in 2026, and is projected to grow at about 17.8% CAGR. The region has a much larger underlying steel production base, so even modest substitution creates substantial demand. India is particularly exposed because its average crude-steel emissions intensity is around 2.55 tonnes of CO2 per tonne compared with a global average of 1.85 tonnes, increasing the urgency of technology upgrades where exports face carbon-related costs. For example, Tata Steel is advancing low-carbon production initiatives while Nippon Steel is commercializing NSCarbolex Neutral and extending green-steel adoption into automotive applications. Demand is therefore growing through both export protection and domestic decarbonization.
North America is estimated at 19.4% of the 2026 market, or approximately USD 1.67 billion, with an expected 16.9% CAGR. The United States has strong demand potential in automotive, construction and infrastructure, but adoption remains more uneven because customers have shown resistance to paying higher prices. The Cleveland-Cliffs case is instructive: the U.S. Department of Energy said the company changed the original project scope because customers were unwilling to pay the green premium. Demand is still expanding through recycled-steel EAF production and lower-carbon product certification, creating a market that is commercially active but highly price conscious.
The Middle East and Africa region is estimated to hold 7.1% of 2026 value, around USD 0.61 billion, and grow at approximately 17.5% CAGR. Demand is being supported by abundant solar resources, export-oriented industrial strategies, new direct-reduction investments and the region’s long-standing use of DRI-EAF production. Producers are increasingly positioned to supply lower-carbon steel into Europe and other carbon-sensitive markets, especially where renewable electricity can reduce operating costs.
Latin America accounts for an estimated 5.2% share of the 2026 Green Steel Market, or USD 0.45 billion, and is projected to expand at about 15.8% CAGR. Growth is being shaped by renewable electricity availability, mining integration and the potential to combine high-quality iron resources with low-carbon power. The region remains earlier in commercial adoption than Europe, but lower-emission iron and steel projects can gain traction as export customers tighten carbon requirements and developers seek differentiated products.
How Competitive Strategies Are Redefining the Green Steel Market
Competition is increasingly divided between established steelmakers building low-carbon product portfolios and specialist developers attempting to establish entirely new production routes. The strongest competitive position is no longer determined only by steelmaking scale. Access to clean electricity, scrap, high-grade iron ore, hydrogen, certification and long-term offtake contracts is becoming equally important. Stegra’s advance sales demonstrate how securing customers can underpin project development, while the wider industry is showing two competing commercial models: incremental emissions reduction through existing assets and full technology transformation through DRI-EAF or other breakthrough processes.
ArcelorMittal operates XCarb, covering reduced-, low- and zero-carbon steel initiatives. Its portfolio includes XCarb recycled and renewably produced flat and long products, XCarb steel certificates, structural sections, beams, plates, coated products and other construction-oriented grades.
SSAB combines SSAB Zero and its HYBRIT-based fossil-free steel program. Its portfolio spans fossil-free and recycled steel, high-strength Strenx structural steels, Hardox wear plate and steel solutions for trucks, construction equipment, infrastructure and energy applications.
Salzgitter AG markets SALCOS green steel and is converting its integrated production route toward direct reduction and electric arc furnaces. Its commercial range includes low-carbon steel for construction, plant engineering, mechanical engineering and wider flat-steel applications, supported by product carbon-footprint certification.
thyssenkrupp Steel offers bluemint Steel, including bluemint pure and bluemint recycled, alongside its established flat-steel portfolio. Product coverage includes hot strip, high-strength automotive grades, packaging steel, electrical steel and other specialized flat products.
Nucor Corporation markets Econiq certified low-embodied-carbon steel across its steel and fabricated-steel portfolio. Its offering includes net-zero and renewable-electricity pathways, allowing the certification to be applied across a broad range of finished steel products.
voestalpine commercializes greentec steel editions across flat steel, including electrical steel and high-strength grades used in automotive, machinery, appliances and energy-related applications. Its strategy combines near-term process efficiency with EAF deployment and longer-term hydrogen-based production.
Tata Steel is developing multiple low-carbon pathways, including HIsarna technology and hydrogen-related initiatives, while maintaining a broad portfolio serving automotive, construction, engineering and industrial markets. Its decarbonization strategy covers both European and Indian operations.
Nippon Steel offers NSCarbolex Neutral and NSCarbolex Solution, combining lower-carbon steel procurement with products and technologies designed to reduce emissions during customer manufacturing and product use. The portfolio covers automotive, infrastructure, machinery, energy, pipes and tubes, structural steel and other specialized products.
Stegra is positioned as a dedicated near-zero steel producer built around green hydrogen, direct reduction and electric steelmaking. Its commercial model is focused on supplying low-carbon steel to customers that have already committed future volumes, making long-term offtake agreements a central part of its go-to-market strategy.
Emirates Steel Arkan (EMSTEEL) represents another important regional route through DRI-based steelmaking, with a product base spanning reinforcement steel, wire rod and heavy sections. Its location and production structure provide a potential platform for supplying lower-carbon steel into Middle Eastern infrastructure and export markets.