

Construction Equipment Rental Market (2025-2034)
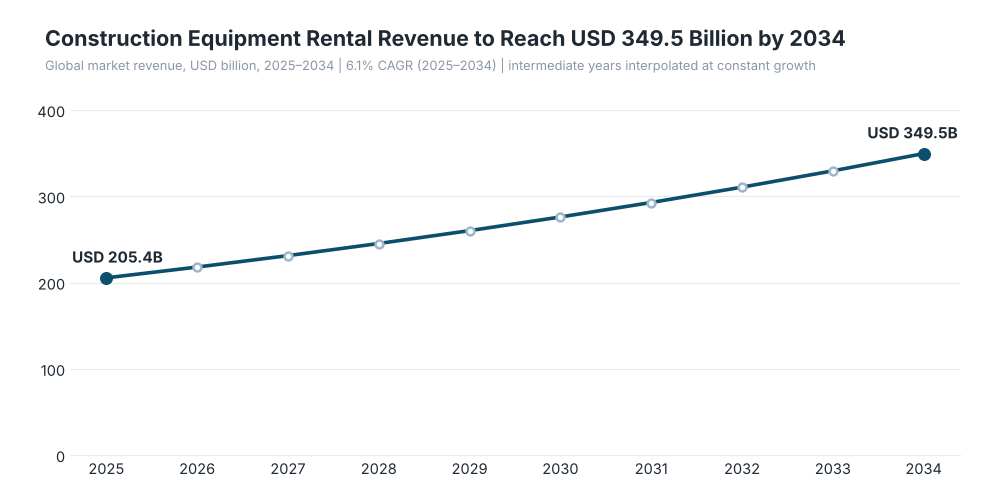
The Global Construction Equipment Rental Market was estimated at approximately USD 205.4 billion in 2025 and is projected to reach about USD 349.5 billion by 2034, advancing at a CAGR of 6.1%.



Quick Enquiry
How Large Is the Construction Equipment Rental Market and What Is Fueling Its Expansion?
The Global Construction Equipment Rental Market was estimated at approximately USD 205.4 billion in 2025 and is projected to reach about USD 349.5 billion by 2034, advancing at a CAGR of 6.1%. The market covers the temporary use of excavators, loaders, cranes, aerial platforms, telehandlers, compactors, concrete equipment and related machinery by contractors, infrastructure developers and industrial operators. Demand is rising because rental converts large equipment purchases into flexible operating costs, avoids idle-fleet ownership and gives contractors faster access to specialized machinery when projects change. The shift is already visible in the U.S., where construction and industrial equipment rental penetration reached 59.5% in 2025, while the combined construction and industrial equipment and general tool rental market reached USD 80.6 billion.
Infrastructure expansion, data-center construction, energy projects, road development and industrial maintenance are widening equipment applications. Earthmoving remains the volume engine, while specialty equipment is gaining importance as projects demand temporary power, climate control, fluid management, access and lifting solutions. United Rentals’ specialty rental revenue increased 27.0% year over year in Q2 2024, reinforcing where premium demand is developing.
Key Report Takeaways
- Earthmoving equipment remains the dominant equipment-type subsegment, representing an estimated 43.0% share of the 2025 market, while material handling equipment is the faster-expanding subsegment at an estimated 6.8% CAGR through 2034 as warehousing, industrial construction and multi-story projects increase demand.
- General construction rentals account for an estimated 74.0% share of rental-category revenue in 2025, but specialty rentals are advancing faster at roughly 8.7% CAGR, supported by power, HVAC, trench, pumping and other engineered jobsite requirements.
- Construction and infrastructure applications hold the largest application share at about 79.0% in 2025, whereas industrial and utility projects are projected to post the stronger 7.0% CAGR as factories, energy assets and large-scale infrastructure require temporary equipment without permanent fleet ownership.
- Short-term and project-based rentals command an estimated 61.0% share of rental activity, while longer-duration contract rentals are expected to grow at around 6.9% CAGR as major projects increasingly secure dedicated equipment pools.
- North America leads the geographic market with an estimated 36.6% share in 2025, while Asia Pacific is expected to record the highest regional growth at approximately 7.6% CAGR through 2034 as urban infrastructure, industrialization and equipment financing constraints support rental adoption.
- Standard earthmoving machines generate most rental volume, but specialty solutions are moving up the value chain, with United Rentals reporting 27.0% year-over-year growth in specialty rental revenue during Q2 2024.
Construction Equipment Rental Market Regulations and Safety Standards Shaping Global Demand
Regulation has a direct effect on which machines rental companies can place into service, how they must be inspected and what documentation customers require. In the U.S., OSHA construction rules require employers to maintain safety programs and conduct frequent, regular inspections of jobsites, materials and equipment. Crane and derrick operations fall under OSHA 29 CFR 1926 Subpart CC, which covers inspections, ground conditions, assembly, power-line safety, operational aids, fall protection and operator training. Aerial lifts are governed under 29 CFR 1926.453, with requirements covering authorized operation, load limits, maintenance and fall protection.
Environmental compliance is also changing fleet economics. EPA Tier 4 standards govern emissions from new nonroad diesel engines used in excavators, loaders, forklifts, generators and related machinery, encouraging rental fleets to replace older, higher-emitting equipment with cleaner models.
In Europe, Regulation (EU) 2023/1230 will apply from 20 January 2027, replacing the Machinery Directive framework and strengthening machinery health, safety and conformity requirements.
Construction Equipment Rental Market Growth Across Equipment Types
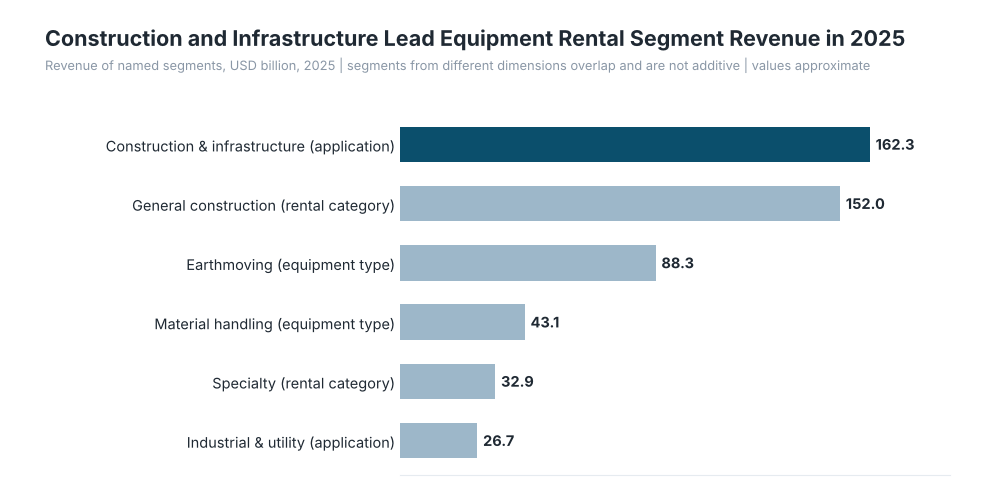
Earthmoving equipment represents an estimated 43.0% of global construction equipment rental revenue in 2025, equal to roughly USD 88.3 billion, with a projected CAGR of 5.8% through 2034. Excavators, loaders, skid-steer loaders and backhoe equipment dominate because almost every major construction project requires excavation, grading, trenching or site preparation. The breadth of applications also keeps utilization comparatively resilient across commercial, residential, civil and infrastructure work. For example, United Rentals and Sunbelt Rentals maintain broad earthmoving fleets covering excavators, loaders and compact equipment, allowing contractors to source different machine classes through established branch networks rather than purchase assets for intermittent use. United Rentals generated USD 13.03 billion in equipment rental revenue in 2024, while Ashtead reported USD 9.63 billion in group rental revenue, illustrating the scale created by broad fleet coverage.
Material handling equipment is estimated at a 21.0% market share in 2025, worth around USD 43.1 billion, and is expected to expand at approximately 6.8% CAGR through 2034. Telehandlers, forklifts, rough-terrain forklifts and related lifting equipment are benefiting from denser construction sites, industrial facilities, warehouses and infrastructure projects where movement of materials is as important as excavation. The growth is not limited to conventional building activity. Riwal has built its rental portfolio around aerial work platforms, telehandlers and forklifts, while Kiloutou combines material-handling equipment with access, utility vehicles and broader construction machinery, reflecting the industry's movement toward one-stop rental procurement.
Construction Equipment Rental Market Shift Toward General and Specialty Rental Models
General construction equipment remains the largest rental-category subsegment, accounting for an estimated 74.0% share and approximately USD 152.0 billion in 2025, with a CAGR of 5.6% through 2034. The category continues to benefit from straightforward customer economics: contractors can rent machines for a project, return them after completion and avoid depreciation, storage and long-term financing exposure. Scale matters heavily here because nearby fleet availability reduces transportation costs and improves replacement speed. Sunbelt Rentals and Herc Rentals have both expanded dense local networks to support this model, while H&E Equipment Services continues to focus on construction and industrial equipment including aerial work platforms, material handling machinery and heavy equipment. Herc reported more than 450 North American locations and approximately USD 7 billion of fleet at year-end 2024.
Specialty rentals are estimated to account for about 16.0% of the market in 2025, or nearly USD 32.9 billion, yet they are expected to achieve the strongest growth at around 8.7% CAGR through 2034. This is where rental companies increasingly sell a solution rather than a machine. Demand is building for temporary power, climate control, pumps, trench safety and fluid-management systems on technically demanding projects. United Rentals' specialty segment recorded 27.0% year-over-year rental revenue growth in Q2 2024, reaching USD 1.006 billion for the quarter, providing a clear commercial signal that specialty categories can outpace general rental demand. For example, United Rentals and Ashtead have both expanded specialty capabilities around power, HVAC and project-specific services, making them more embedded in large industrial and infrastructure work.
Construction Equipment Rental Market Applications Expanding Beyond Traditional Building Activity
Construction and infrastructure applications remain the core demand center, with an estimated 79.0% share of global rental revenue in 2025, equivalent to around USD 162.3 billion, and a projected CAGR of 5.9% through 2034. Road construction, commercial development, housing, utilities, bridges and large public works continue to require machines in changing combinations throughout the project lifecycle. Rental demand increases when contractors cannot justify owning a full fleet for every phase. For example, Kiloutou serves earthmoving, demolition, elevation, handling, energy and site-development requirements across construction and civil-engineering projects, while Kanamoto positions construction equipment rental as its core business with roughly 5,000 equipment models and 1.8 million rental items across its group.
Industrial and utility applications are smaller, with an estimated 13.0% share and approximately USD 26.7 billion in 2025, but this segment is projected to grow at around 7.0% CAGR through 2034. Manufacturing plants, power infrastructure, logistics facilities, semiconductor projects and energy installations often require cranes, pumps, access equipment, temporary power and specialty machinery for defined installation or maintenance windows. Firms such as Maxim Crane Works, Riwal and EquipmentShare illustrate the broader application mix, ranging from heavy lifting to access equipment and connected rental solutions. EquipmentShare's technology-driven model also demonstrates how rental services are increasingly tied to fleet visibility, utilization and jobsite data rather than simple equipment handover.
Construction Equipment Rental Market Regional Expansion and Demand Outlook
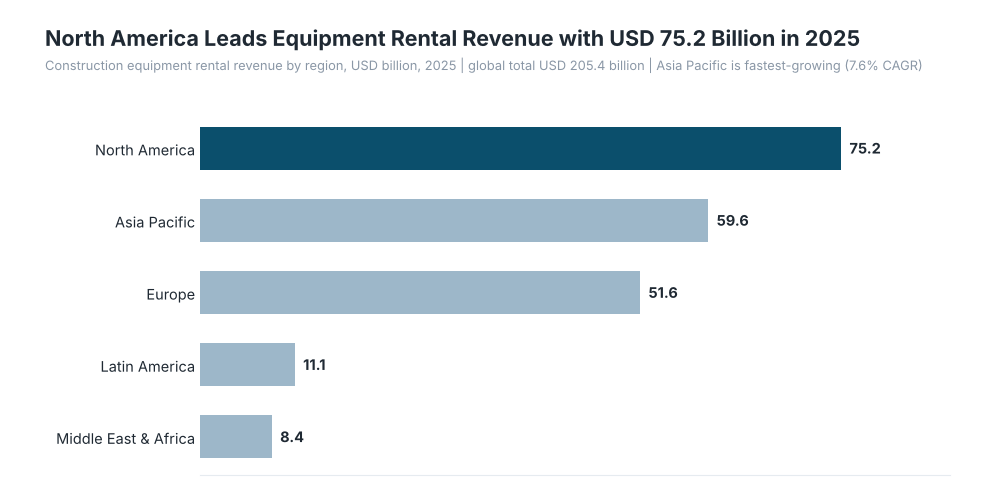
North America held an estimated 36.6% share of the global market in 2025, representing about USD 75.2 billion, and is expected to expand at approximately 5.4% CAGR through 2034. The region leads because rental is already deeply embedded in contractor procurement, supported by mature branch networks, large infrastructure programs and high equipment ownership costs. U.S. rental penetration reaching 59.5% shows that renting is no longer simply a solution for temporary shortages; for many contractors it has become a standard operating model. For example, United Rentals continues to operate a broad general and specialty fleet, while Herc expanded its branch network by 14% in 2024 through acquisitions and greenfield openings, taking its network to 451 locations.
Asia Pacific is estimated to account for 29.0% of the market in 2025, or approximately USD 59.6 billion, and is projected to deliver the fastest regional CAGR at around 7.6% through 2034. Demand is rising as urban development, transport infrastructure, industrial facilities and large-scale construction projects expand while equipment ownership remains financially challenging for many small and mid-sized contractors. Japan provides an especially mature rental model, with Kanamoto operating an extensive construction-focused portfolio, while Nishio Rent All offers construction DX equipment, civil-engineering machinery, road machinery, lifting equipment, generators, pumps and environmental equipment. Their portfolios show how Asian rental markets are moving toward wider equipment coverage and technology-led site support.
Europe represented an estimated 25.1% share in 2025, worth nearly USD 51.6 billion, and is projected to grow at around 4.7% CAGR through 2034. The market is more mature and therefore slower-growing than Asia Pacific, but rental demand is supported by infrastructure renewal, construction activity, energy projects and tighter equipment-emissions requirements. The European rental market is also becoming more professionalized, with large operators using dense networks and broader product ranges to compete on availability and service rather than price alone. For example, Kiloutou operates hundreds of branches across Europe with a diversified rental range spanning earthmoving, access, utility vehicles, tools and light equipment, while Loxam continues to compete through broad construction and industrial rental capabilities.
Latin America held an estimated 5.4% market share in 2025, equivalent to approximately USD 11.1 billion, and should grow at about 5.9% CAGR through 2034. Rental demand is being supported by infrastructure construction, mining, road development and contractor demand for lower upfront capital commitments. Growth remains uneven because local financing conditions and economic cycles can quickly affect project starts, keeping fleet utilization more volatile than in North America or Western Europe.
The Middle East and Africa accounted for an estimated 4.1% share in 2025, around USD 8.4 billion, and is expected to expand at approximately 6.4% CAGR through 2034. Large infrastructure, transport, energy, tourism and urban-development projects create demand for heavy lifting, access and earthmoving equipment, while project-specific procurement makes rentals attractive for contractors unwilling to build permanent fleets. The region's strongest opportunities are concentrated around large projects rather than broad-based small contractor demand.
Construction Equipment Rental Market Competitive Landscape and Portfolio Positioning
Competition is increasingly split between broad-line rental companies with dense branch networks and specialists that build positions in high-value equipment categories. The scale leaders are using acquisitions, greenfield branches, technology and specialty capabilities to improve utilization and capture a larger share of project spending. Ashtead invested USD 4.3 billion in its business and completed 26 bolt-on acquisitions in fiscal 2024, while United Rentals spent approximately USD 3.76 billion on gross rental capital expenditures, underscoring how difficult it is for smaller providers to match fleet depth and geographic availability.
United Rentals: Its portfolio spans general construction machinery, aerial equipment, earthmoving, material handling, specialty power and HVAC, trench solutions, pumps, tools and worksite services, giving the company exposure across both standard and premium rental categories.
Ashtead Group / Sunbelt Rentals: The group combines earthmoving and general tool rentals with specialty businesses covering areas such as power, HVAC and other project-focused services across the U.S., Canada and the UK. Its portfolio strategy increasingly targets large projects and broader customer relationships.
Herc Rentals: Herc provides construction and industrial equipment including aerial work platforms, earthmoving machines, material handling equipment, compaction products, trucks, trailers, pumps, power equipment and other specialty solutions. Its growing branch density supports rapid local fulfillment.
H&E Equipment Services: H&E focuses on construction and industrial rental equipment, particularly heavy equipment, aerial work platforms, cranes and material-handling machinery, with service and support capabilities built around its rental network.
EquipmentShare: The company combines construction equipment rental with connected jobsite technology, fleet tracking and digital equipment-management capabilities. Its T3 platform and capital-light OWN program distinguish the model from traditional branch-only rental approaches.
Loxam: Loxam competes across construction, civil engineering, industry and infrastructure with a broad rental portfolio covering earthmoving, access, lifting, temporary site requirements and complementary equipment.
Boels Rentals: Boels offers a diversified equipment rental portfolio covering construction machinery, access equipment, tools, transport, temporary site solutions and specialist equipment, with geographic scale across European markets.
Kiloutou: Kiloutou provides earthmoving, access, material handling, utility vehicles, energy and climate equipment, demolition machinery, professional tools and site-development equipment, supporting a one-stop procurement model.
Kanamoto: Kanamoto is heavily concentrated in construction equipment rental and maintains a broad portfolio covering construction machinery, temporary site materials, DX-related equipment and related worksite products, supporting consolidated procurement for contractors.
Nishio Rent All: Nishio combines civil-engineering and construction equipment with road-paving machinery, access equipment, lifting and transport products, generators, pumps, environmental equipment, measurement systems and construction-DX solutions.
Riwal: Riwal specializes in access solutions, with aerial work platforms, telehandlers and forklifts forming the core of its rental fleet, making it particularly relevant to projects where work-at-height and material positioning are critical.
Maxim Crane Works: Maxim focuses on specialist heavy lifting, offering all-terrain, crawler, hydraulic truck, rough-terrain, tower, boom and carry-deck cranes alongside lifting services and used equipment sales.