

Automotive Semiconductor Market (2025-2034)
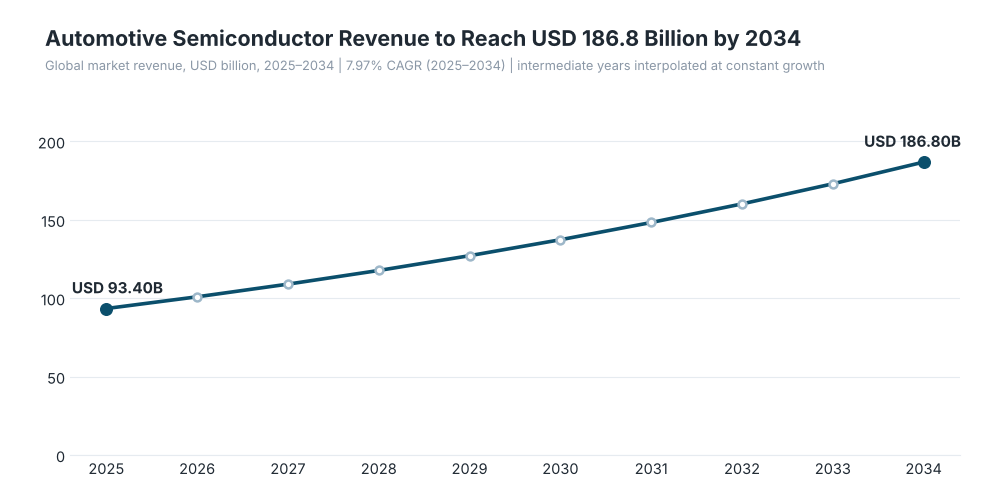
The Global Automotive Semiconductor Market was estimated at USD 93.40 billion in 2025 and is projected to reach USD 186.80 billion by 2034, advancing at a CAGR of 7.97% from 2025 to 2034.



Quick Enquiry
How Large Is the Automotive Semiconductor Market and What Is Fueling Its Expansion?
The Global Automotive Semiconductor Market was estimated at USD 93.40 billion in 2025 and is projected to reach USD 186.80 billion by 2034, advancing at a CAGR of 7.97% from 2025 to 2034. The estimate is derived from the long-range KPMG automotive semiconductor outlook and its underlying growth trajectory rather than copied from syndicated market-research estimates.
Automotive semiconductors are the electronic building blocks behind vehicle control, sensing, connectivity, safety, power conversion, and increasingly AI-based driving functions. Demand is rising as vehicles carry more digital functions per platform. In 2025, global electric-car sales exceeded 20 million units and represented one-quarter of new-car sales, creating a larger installed base for battery-management, inverter, charging, sensing, and power-management chips.
The bigger change is happening inside the vehicle. ADAS and autonomous-driving processing semiconductors are estimated at USD 5.60 billion in 2025 and could approach USD 46 billion by 2035, while their share of automotive semiconductor value rises from below 6% to about 22%. EVs also carry more semiconductor value per vehicle, with McKinsey estimating more than USD 1,000 of content versus roughly USD 330 in conventional ICE vehicles.
Key Report Takeaways
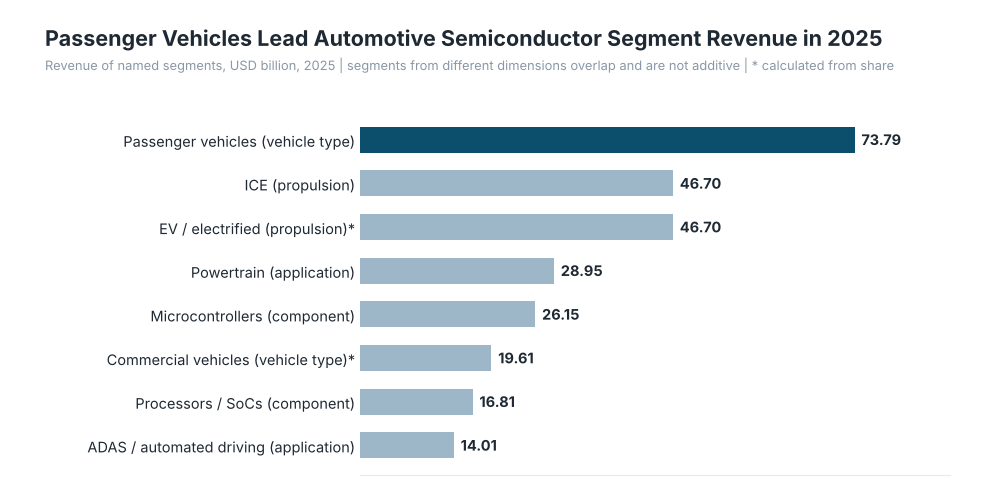
- In the component mix, microcontrollers remain dominant with an estimated 28.0% market share and USD 26.15 billion in 2025 at a 6.4% CAGR, while processors and automotive SoCs are the fastest-growing pool at about 18.0% share and a projected 15.8% CAGR as centralized compute expands.
- Passenger vehicles command approximately 79.0% of automotive semiconductor demand, equivalent to about USD 73.79 billion in 2025 and a 7.6% CAGR, whereas commercial vehicles are expanding faster at an estimated 9.2% CAGR from a 21.0% share as electric trucks and advanced fleet electronics gain traction.
- ICE platforms still represent an estimated 50.0% share and USD 46.70 billion of 2025 semiconductor demand, growing around 3.0% annually, while EV and electrified platforms are the fastest-moving propulsion pool with an estimated 50.0% share and 12.5% CAGR as silicon content rises with power conversion and battery systems.
- Powertrain remains the largest application at an estimated 31.0% share and USD 28.95 billion in 2025 with a 6.5% CAGR, while ADAS and automated-driving electronics are the fastest-growing application at roughly 15.0% share and about 19.8% CAGR as sensor fusion and in-vehicle AI become more capable.
Automotive Semiconductor Market Standards Reshaping Safety, Cybersecurity, and Software-Defined Vehicles
Automotive semiconductor demand is increasingly influenced by vehicle-level safety, cybersecurity, software-update, and component-quality requirements. ISO 26262 remains the core functional-safety framework for safety-related electrical and electronic systems, covering management, concept development, hardware, software, production, operation, and decommissioning. The standard directly raises the importance of safety-oriented semiconductor design and lifecycle processes because chips are embedded in systems where failure can affect vehicle safety.
Cybersecurity is becoming equally important. ISO/SAE 21434 establishes engineering requirements for cybersecurity risk management across the vehicle E/E lifecycle and works alongside functional-safety processes rather than replacing them.
At the regulatory level, UN Regulation No. 155 addresses vehicle cybersecurity and cybersecurity-management systems, while UN Regulation No. 156 governs vehicle software updates and software-update management systems. Both entered into force in 2021 and have continued to receive amendments, increasing pressure on OEMs and suppliers to maintain traceable, secure electronic architectures.
These requirements support demand for secure MCUs, safety processors, hardware security modules, authenticated communication devices, and update-capable central computing platforms. Automotive semiconductors therefore increasingly compete on compliance, reliability, security, and lifecycle support, not processing performance alone.
Automotive Semiconductor Market by Component Type: Compute Is Taking a Larger Share of Vehicle Silicon
Microcontrollers represented an estimated 28.0% of the automotive semiconductor market in 2025, or about USD 26.15 billion, with a projected 6.4% CAGR through 2034. Their scale comes from broad deployment across body control, braking, powertrain, chassis, battery management, gateways, and safety functions. MCUs remain difficult to displace because vehicles still need large numbers of deterministic controllers even as architectures become more centralized. Companies such as NXP Semiconductors, Renesas Electronics, and STMicroelectronics continue to build extensive automotive MCU portfolios spanning real-time control, safety, body electronics, electrification, and domain applications.
Processors and automotive SoCs are the fastest-growing component category, estimated at about 18.0% share and USD 16.81 billion in 2025, with a projected 15.8% CAGR. The change is structural. Centralized vehicle computers, multi-sensor perception, cockpit consolidation, and AI inference require much higher compute density than conventional ECU architectures. For example, Qualcomm’s Snapdragon Ride family combines high-performance processing with AI acceleration for ADAS and automated-driving workloads, while Ambarella’s CV3-AD family targets multi-sensor perception and path planning from L2+ through L4 systems.
Automotive Semiconductor Market by Vehicle Type: Passenger Platforms Lead While Commercial Electronics Intensify
Passenger vehicles accounted for an estimated 79.0% of automotive semiconductor demand in 2025, representing approximately USD 73.79 billion and a 7.6% CAGR. Their lead reflects sheer production volume and the rapid addition of ADAS, digital cockpits, connected functions, electrified powertrains, and advanced safety systems. Demand is increasingly tied to higher electronic content per platform rather than only unit sales, with EV adoption providing an additional lift. China alone produced around 16 million electric cars in 2025, highlighting the scale of vehicle-electronics deployment in the passenger segment.
Commercial vehicles held a smaller estimated 21.0% share in 2025 but are projected to expand at about 9.2% CAGR. Fleets are adopting electrified drivetrains, automated safety systems, telematics, fleet connectivity, and energy-management electronics. Sales of electric heavy-freight trucks tripled globally in 2025 to more than 200,000 units, strengthening the business case for higher-value power and control semiconductors outside passenger cars. Early innovation includes semiconductor platforms from Infineon Technologies and NXP Semiconductors that address high-voltage power conversion, vehicle networking, real-time processing, and electric commercial-vehicle control.
Automotive Semiconductor Market by Propulsion Type: Electrification Is Expanding the Silicon Bill of Materials
ICE vehicles are estimated to account for roughly 50.0% of automotive semiconductor demand in 2025, or USD 46.70 billion, with a restrained 3.0% CAGR through 2034. The segment remains substantial because internal-combustion platforms still use substantial electronics for engine control, transmission management, emissions systems, safety, power distribution, and connected features. However, its semiconductor expansion is increasingly incremental rather than transformational. Firms such as Microchip Technology, STMicroelectronics, and Renesas continue to supply MCUs, analog devices, power devices, and control technologies across conventional powertrain and chassis systems.
Electrified vehicles represent the fastest-moving propulsion opportunity, with an estimated 50.0% share of 2025 semiconductor demand and a projected 12.5% CAGR. The growth comes from the multiplication of electronic control points across batteries, inverters, onboard chargers, DC-DC conversion, thermal management, and high-voltage distribution. McKinsey estimates semiconductor content above USD 1,000 in a standard EV compared with around USD 330 for an ICE vehicle. For example, Infineon Technologies develops automotive SiC and GaN power switches, gate drivers, microcontrollers, sensors, and power-management devices, while STMicroelectronics supplies SiC MOSFETs, IGBTs, gate drivers, MCUs, and charging-related power electronics for electric and hybrid vehicles.
Automotive Semiconductor Market by Application: ADAS Becomes the Fastest Route to Higher Chip Value
Powertrain applications remained the largest automotive semiconductor use case in 2025, with an estimated 31.0% share, equal to approximately USD 28.95 billion, and a projected 6.5% CAGR. Powertrain demand spans engine control, battery management, inverter control, charging, motor management, and power conversion, making it one of the most persistent semiconductor-consuming areas in the vehicle. Key players such as Infineon Technologies and STMicroelectronics serve this market through MCUs, PMICs, gate drivers, sensors, SiC devices, IGBTs, and other power components.
ADAS and automated-driving applications are estimated at about 15.0% of the market in 2025, or USD 14.01 billion, but are expected to grow at roughly 19.8% annually through 2034. The commercial shift is being led by central computing, sensor fusion, machine-learning acceleration, automated parking, driver monitoring, and higher levels of driving automation. McKinsey’s forecast of ADAS/autonomous-driving processing rising from USD 5.6 billion in 2025 to USD 46 billion in 2035 demonstrates how rapidly premium semiconductor value is moving toward compute-intensive vehicle intelligence. For instance, NVIDIA develops automotive accelerated-computing platforms for automated driving and cockpit workloads, while Qualcomm Technologies and Ambarella are expanding scalable ADAS and centralized AI-processing platforms for software-defined vehicles.
Automotive Semiconductor Market Regional Outlook: Production Scale and Localization Define the Next Growth Cycle
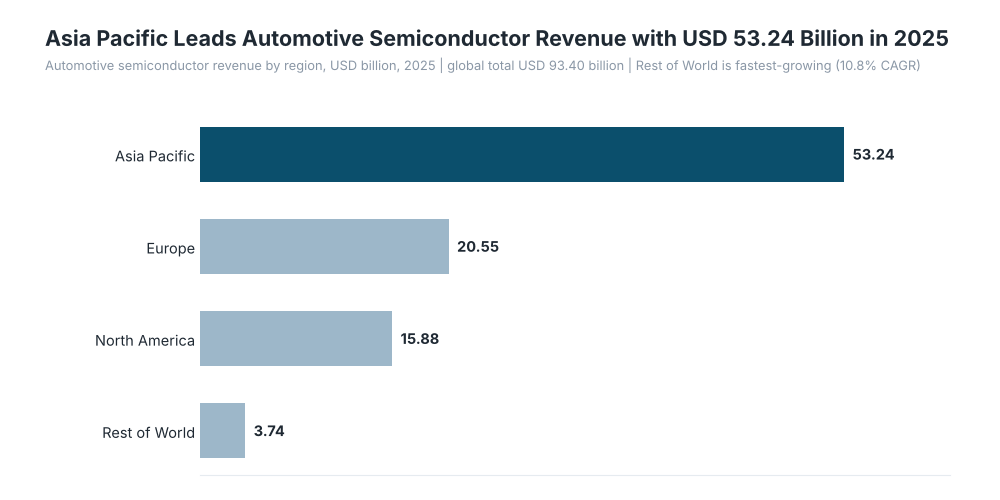
Asia Pacific accounted for an estimated 57.0% of global automotive semiconductor demand in 2025, representing about USD 53.24 billion, and is projected to grow at a 9.1% CAGR through 2034. China is the region’s center of gravity because of its vehicle production scale, EV concentration, battery ecosystem, and growing domestic semiconductor integration. Nearly 22 million electric cars were produced globally in 2025, with China accounting for about 75% of production, while China also exceeded 16 million units of electric-car output itself. For example, Renesas Electronics and NXP Semiconductors serve automotive compute, control, networking, and safety applications, while the broader regional production base continues to pull demand toward localized automotive-grade silicon.
Europe held an estimated 22.0% share in 2025, equivalent to USD 20.55 billion, with a projected 7.3% CAGR. Demand is being supported by vehicle electrification, stricter emissions requirements, functional-safety expectations, and rising electronics content in new vehicle programs. European electric-car sales rose by more than 30% in 2025 to reach 28% of new-car sales, strengthening demand for power-management and charging semiconductors. For example, Infineon Technologies supplies automotive MCUs, power semiconductors, sensors, memories, networking devices, and security technologies, while STMicroelectronics addresses electrified powertrains, battery management, charging, and automotive control.
North America represented an estimated 17.0% of the market in 2025, or USD 15.88 billion, advancing at approximately 6.4% CAGR. Growth is increasingly concentrated in high-value ADAS, premium vehicle computing, electrification, commercial fleets, and software-defined architectures rather than broad unit expansion. For example, NVIDIA and Qualcomm Technologies are strengthening the regional ecosystem around centralized automotive computing, while Texas Instruments supports vehicle power management, sensing, connectivity, and analog-intensive electronic architectures.
The rest of the world accounted for the remaining estimated 4.0% share, or about USD 3.74 billion, with a projected 10.8% CAGR. Demand is rising from vehicle assembly expansion, imported EV platforms, fleet modernization, and the electrification of commercial transport. Southeast Asia is particularly notable, with electric-car sales more than doubling in 2025 as Thailand and Viet Nam helped drive regional adoption.
Automotive Semiconductor Market Competition: Portfolios Are Expanding From Chips Into Vehicle Architecture
Competition is no longer defined only by who supplies the most MCUs. The strongest positions increasingly come from companies that can cover compute, power, networking, safety, sensing, and software together. That favors diversified automotive semiconductor groups, while specialist AI and autonomy suppliers are competing for the highest-value layers of the vehicle architecture.
NXP Semiconductors
NXP’s automotive portfolio spans S32 microcontrollers and processors, vehicle-network processors, zonal controllers, Ethernet switches, safety processors, power-management devices, and secure connectivity. Its S32 platform is designed around the shift toward centralized and zonal vehicle architectures, making it particularly relevant to software-defined vehicles and real-time automotive control.
Infineon Technologies
Infineon covers a broad automotive stack that includes AURIX and TRAVEO microcontrollers, power-management ICs, SiC and GaN power devices, gate drivers, sensors, memories, networking components, and security technologies. Its positioning is especially strong across electrification, power distribution, vehicle control, and automated-driving infrastructure.
Renesas Electronics
Renesas supplies R-Car SoCs, RH850 automotive MCUs, power-management devices, sensing solutions, and embedded control technologies. Its automotive portfolio targets ADAS, vehicle control, safety, electrification, and next-generation centralized processing architectures.
STMicroelectronics
STMicroelectronics offers automotive MCUs, SiC MOSFETs and diodes, IGBTs, gate drivers, power-management components, sensors, and electrification solutions. Its portfolio spans propulsion, battery management, charging, body electronics, chassis, and safety-related applications.
Texas Instruments
Texas Instruments participates across automotive analog and embedded processing, with products addressing power management, battery monitoring, sensing, signal-chain functions, automotive networking, and advanced driver-assistance architectures.
onsemi
onsemi focuses strongly on automotive power and sensing, including silicon carbide technologies, power modules, image sensors, and related devices used in electrification and intelligent-vehicle systems.
Qualcomm Technologies
Qualcomm’s automotive portfolio increasingly centers on Snapdragon Ride SoCs and associated software for ADAS, automated driving, cockpit integration, and centralized compute. Snapdragon Ride Flex is designed to combine ADAS and cockpit workloads within a unified SoC architecture.
NVIDIA
NVIDIA competes at the high end of automotive computing through accelerated platforms designed for automated driving, AI inference, sensor processing, and digital cockpit workloads, targeting the growing premium compute layer of software-defined vehicles.
Mobileye
Mobileye specializes in ADAS and autonomous-driving technologies centered on its EyeQ family of automotive system-on-chips and related perception and driving software, giving it a focused position in vehicle intelligence.
Ambarella
Ambarella brings low-power AI processing into automotive applications through its CV3-AD family, which supports multi-sensor perception, fusion, path planning, driver monitoring, parking, and autonomous-driving workloads from L2+ through L4.
Microchip Technology
Microchip maintains a wide automotive portfolio spanning MCUs, analog products, memory, connectivity, automotive access, and embedded-control technologies. Its automotive components are designed for long-life vehicle applications and automotive qualification requirements.
Robert Bosch
Bosch operates across automotive electronics with semiconductor and sensor technologies supporting mobility applications, including MEMS sensing, power semiconductors, vehicle control, and safety-oriented electronics.
Automotive Semiconductor Market Strategic Outlook
The next phase of automotive semiconductor growth will be defined less by the number of chips installed and more by the value of the functions those chips perform. EV adoption is widening the power-electronics opportunity. ADAS is pulling semiconductor spending toward AI compute. Zonal and centralized architectures are changing where control processing sits inside the vehicle. At the same time, cybersecurity, functional safety, and software-update requirements are raising the qualification threshold for every critical electronic component. The market therefore presents a split opportunity: mature controllers remain essential for volume, but the strongest value creation is moving toward processors, power semiconductors, sensing, networking, and integrated computing platforms. KPMG’s projection of roughly USD 200 billion in annual automotive semiconductor revenue by the mid-2030s, with a path beyond USD 250 billion by 2040, reinforces the scale of that structural shift.