

Automotive Insurance Market (2026-2032)
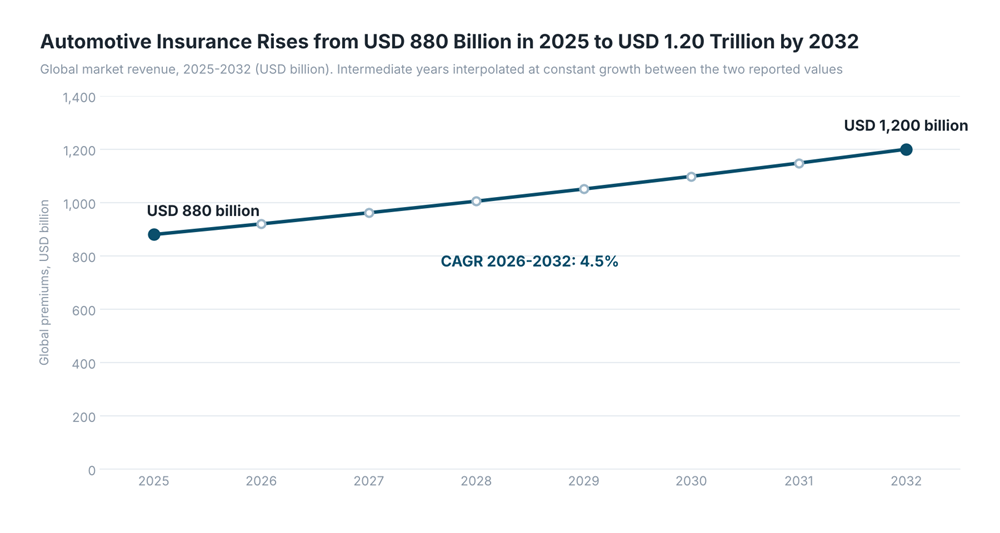
The Global Automotive Insurance Market was valued at an estimated USD 880 billion in 2025 and is projected to reach approximately USD 1.20 trillion by 2032, expanding at an indicative CAGR of 4.5% during 2026-2032.



Quick Enquiry
How Large Is the Global Automotive Insurance Market, and What Is the Outlook Through 2032?
The Global Automotive Insurance Market was valued at an estimated USD 880 billion in 2025 and is projected to reach approximately USD 1.20 trillion by 2032, expanding at an indicative CAGR of 4.5% during 2026-2032, according to MarketsandStats. According to Swiss Re, motor insurance represents approximately 40% of the USD 2.2 trillion global property and casualty insurance industry, making it one of the largest insurance segments worldwide. Private passenger vehicles represent a major source of premium revenue, while commercial vehicle insurance remains important for transport, logistics, and business fleets.
The United States led global automotive insurance expenditure with approximately USD 447.79 billion in direct premiums in 2025, comprising USD 370.69 billion from private passenger insurance and USD 77.10 billion from commercial automotive insurance. Insurance Information Institute statistics based on National Association of Insurance Commissioners (NAIC) data highlight the substantial contribution of passenger vehicle coverage and the importance of commercial automobile liability within the American insurance industry.
Source: Insurance Information Institute – Auto Insurance Statistics
European automotive insurance premiums recorded substantial growth in 2025. France generated approximately USD 35 billion in motor insurance premiums, compared with roughly USD 32.6 billion in 2024. Spain recorded approximately USD 16.6 billion, increasing 8.38%, while Germany reported 13.4% premium growth. Rising vehicle repair expenses and claims costs remained important factors influencing motor insurance premiums across major European markets.
China and Brazil also represent significant automotive insurance markets. China's compulsory motor liability insurance covered approximately 386 million vehicles in 2025, generating around USD 40 billion in premiums. Brazil recorded approximately USD 5.2 billion in motor insurance premiums during the first half of 2025, supported by its substantial passenger and commercial vehicle population.
Rising vehicle repair costs, commercial fleet insurance requirements, and continued motor insurance penetration are shaping premium growth through 2032. Insurers including Progressive, State Farm, Allianz, AXA, and PICC compete across major automotive insurance markets, with claims performance, underwriting profitability, and policyholder retention remaining central to their financial results.
Automotive Insurance Market: Key Report Takeaways
| Market Indicator | Research Finding |
|---|---|
| Global Market Size (2025) | Approximately USD 880 Billion |
| Projected Market Size (2032) | Approximately USD 1.20 Trillion |
| CAGR (2026–2032) | 4.5% |
| Largest National Market | United States |
| Leading Coverage Component in Verified U.S. Data | Motor Liability Insurance |
| Leading Vehicle Category | Passenger Cars |
| Leading Policyholder Category | Individual/Personal Policyholders |
| Leading Application | Personal Vehicle Risk Protection |
| Major Distribution Channels | Agents & Brokers and Direct Insurance Sales |
| Main Commercial Pressures | Repair Costs, Claim Severity, Premium Competition, and Customer Retention |
Why Are Automobile Insurance Premiums Increasing Despite Slower Vehicle Ownership Growth?
Automobile insurance premiums have increased across major markets, with higher vehicle repair costs, replacement parts expenditure, and claims payments contributing to rising insurance spending. The Insurance Information Institute reported average U.S. automobile insurance expenditure of USD 1,282 in 2023, increasing 14% from the previous year. Although premium increases have moderated more recently, collision and comprehensive insurance remain particularly affected by repair expenses.
Source: Insurance Information Institute - Auto Insurance Statistics
Germany recorded 13.4% growth in motor insurance premiums during 2025, according to the German Insurance Association (GDV). Replacement parts prices increased by more than 80% between 2015 and early 2026, compared with approximately 30% consumer price inflation during the same period. German motor insurers returned to a positive underwriting result in 2025 following several years of elevated claims expenditure.
Source: German Insurance Association - Motor Insurance Industry Developments
In the United Kingdom, the Association of British Insurers reported GBP 11.9 billion in motor insurance claims payments during 2025 across approximately 2.5 million claims. Vehicle damage accounted for nearly GBP 7.5 billion, representing around 63% of total claims expenditure. The substantial cost of vehicle repairs remains a major consideration for insurers assessing motor insurance profitability.
Source: Association of British Insurers - Motor Insurance Statistics
France recorded approximately 7.5% growth in motor insurance premiums during 2025, compared with around 1% growth in its insured vehicle population. The difference highlights the significant contribution of higher insurance premiums to market revenue, beyond growth in vehicle ownership. Across mature automotive insurance markets, repair inflation and claims expenditure remain important influences on premium adjustments and underwriting performance.
Source: France Assureurs - Motor Insurance Statistics
Which Coverage Type Commands the Largest Share of Automotive Insurance Revenue?
Liability Insurance Leads with 60.6% of U.S. Motor Insurance Premiums
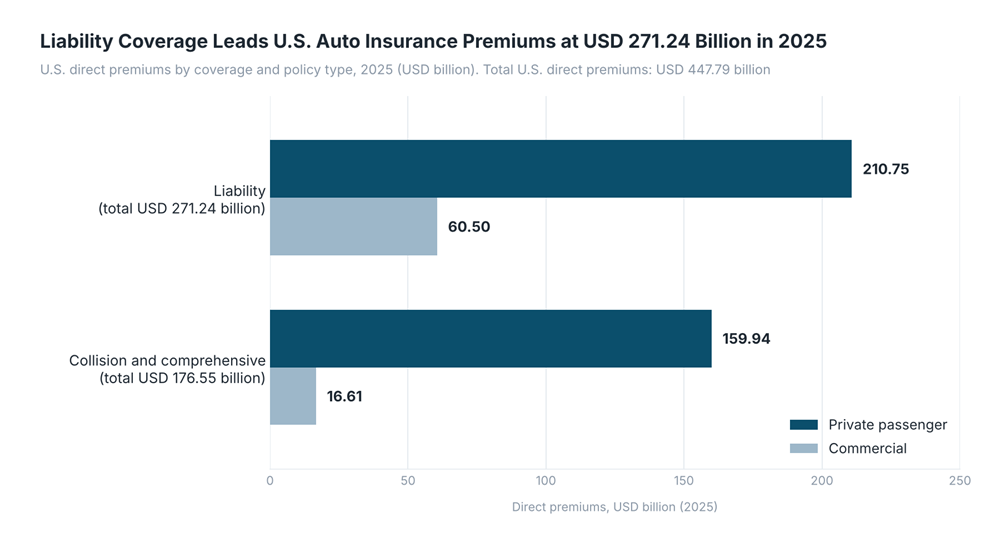
Liability Insurance accounted for approximately USD 271.24 billion in U.S. automotive insurance premiums in 2025, representing 60.6% of the combined private passenger and commercial motor insurance market. Collision and comprehensive physical-damage insurance contributed another USD 176.55 billion. Mandatory third-party liability coverage remains the largest identifiable insurance category, particularly across countries requiring financial protection against road accident injuries and property damage.
According to the Insurance Information Institute, liability insurance accounted for the majority of U.S. direct motor premiums. China also maintains a substantial compulsory insurance market. Its National Financial Regulatory Administration reported CNY 285.2 billion in compulsory motor liability premiums during 2025, increasing 5.2% annually. Coverage extended to approximately 386 million vehicles, including 347 million automobiles.
India requires third-party liability insurance for vehicles operating on public roads. The Insurance Regulatory and Development Authority of India (IRDAI) separately reports liability-only and own-damage insurance, reflecting the distinction between mandatory protection and additional vehicle coverage.
Comprehensive and Own-Damage Insurance Remain Major Revenue Categories
Collision and comprehensive insurance generated approximately USD 176.55 billion in U.S. written premiums during 2025. Private passenger vehicles accounted for USD 159.94 billion, representing more than 90% of physical-damage insurance premiums.
The Insurance Information Institute reported that approximately 80% of insured U.S. drivers carried comprehensive coverage and 77% maintained collision coverage in 2023. These figures highlight the substantial use of vehicle damage protection beyond legally required liability insurance, particularly among owners of financed and higher-value vehicles.
Rising vehicle repair expenditure has become an important consideration for comprehensive insurance providers. Collision claims, replacement parts expenses, and vehicle damage severity continue to influence policy renewals and insurer underwriting performance.
Source: Insurance Information Institute - Auto Insurance Statistics
Why Do Passenger Cars Account for the Largest Vehicle Insurance Category?
Private Passenger Insurance Represents 82.8% of U.S. Motor Premiums
Private Passenger Automobile Insurance generated approximately USD 370.69 billion in U.S. premiums during 2025, accounting for 82.8% of combined private passenger and commercial automotive insurance revenue. Liability protection contributed USD 210.75 billion, while collision and comprehensive insurance accounted for USD 159.94 billion.
France also maintains a substantial personal motor insurance market. Automobile insurance for individual policyholders generated EUR 26.9 billion in 2025, compared with EUR 30.2 billion in total motor insurance premiums. Personal automobile insurance therefore accounted for approximately 89% of the country's reported motor premium revenue.
Private passenger insurance remains an important competitive market for State Farm, Progressive, GEICO, Allstate, Allianz, and other established providers. Annual policy renewals, coverage selection, and customer switching activity are particularly important in this segment.
Commercial Vehicle Insurance Generates USD 77.10 Billion in the United States
Commercial Automotive Insurance accounted for approximately USD 77.10 billion in U.S. direct written premiums during 2025. Commercial liability represented USD 60.50 billion, substantially exceeding collision and comprehensive premiums of USD 16.61 billion.
Freight transportation, logistics, delivery services, vehicle rentals, taxis, buses, and corporate fleets account for important commercial motor insurance expenditure. Commercial automobile liability remains especially significant for businesses operating large fleets and vehicles with substantial third-party accident exposure.
Progressive, Travelers, Berkshire Hathaway, Old Republic, and Zurich are prominent participants in U.S. commercial automotive insurance. Their competitive positions differ from those of private passenger insurers, particularly in fleet underwriting and specialized liability coverage.
Which End Users Generate the Most Automotive Insurance Premiums?
Individual Vehicle Owners Remain the Largest Policyholder Category
Individual vehicle owners account for the largest share of automotive insurance expenditure, with private passenger policies contributing more than four-fifths of U.S. motor premiums. France also recorded a substantial personal insurance contribution, with individual automobile policies representing approximately EUR 26.9 billion of its EUR 30.2 billion motor insurance market in 2025.
Personal automotive insurance expenditure includes liability coverage, collision protection, comprehensive vehicle damage insurance, and applicable personal accident benefits. The category remains central to insurance competition across direct sales, agency distribution, online comparison platforms, and annual policy renewals.
Commercial and fleet operators represent the second major policyholder category. Freight businesses, delivery companies, corporate fleets, and transport operators purchase motor insurance covering multiple vehicles and substantial liability exposure. Fleet contracts remain important for insurers specializing in business transportation risks, including Progressive, Travelers, and Zurich.
How Are Digital Platforms Changing Automotive Insurance Distribution?
Direct insurance sales and online comparison platforms have become important channels for personal automobile insurance, while agents and brokers retain a substantial role in commercial motor coverage.
J.D. Power's 2026 U.S. Insurance Shopping Study reported that 53% of consumers had shopped for automotive insurance, compared with 57% in the previous year. Insurance shoppers obtained an average of 3.5 quotes, while nearly half of newly purchased policies were completed online. Competition among insurers remains substantial, particularly where consumers compare premiums across established national brands.
The 2026 J.D. Power U.S. Auto Insurance Study also reported that 32% of insurance shoppers used AI-assisted tools during their search, while only 58% of surveyed customers said they completely understood their insurance policies. Policy clarity, coverage explanations, and customer service remain important considerations during automobile insurance selection.
India's insurance distribution market is also undergoing regulatory review. Recent IRDAI proposals concerning commissions associated with motor policies distributed through dealerships and intermediaries have drawn attention to acquisition costs and dealership-linked insurance sales.
Source: J.D. Power – Insurance Industry Research
Which Countries Lead the Global Automotive Insurance Market?
United States - Largest Market at USD 447.79 Billion
The United States generated approximately USD 447.79 billion in direct automotive insurance premiums during 2025, comprising USD 370.69 billion in private passenger insurance and USD 77.10 billion in commercial automobile coverage.
State Farm and Progressive remained the leading U.S. personal automobile insurers, with approximately USD 69 billion in direct written premiums each. State Farm held an 18.7% share, narrowly ahead of Progressive at 18.6%. Berkshire Hathaway, including GEICO, accounted for 11.6%, while Allstate represented 10.2%.
Together, these four groups controlled approximately 59.1% of U.S. private passenger automobile premiums. Competition remains substantial following several years of premium increases, particularly in policy renewals, customer retention, claims service, and underwriting profitability.
Source: Insurance Information Institute – Auto Insurance Market
China - 386 Million Vehicles Covered by Compulsory Insurance
China maintains one of the world's largest compulsory motor insurance portfolios. The National Financial Regulatory Administration reported 386 million insured vehicles in 2025, an increase of 3.8%, including approximately 347 million automobiles.
Compulsory motor liability premiums reached CNY 285.2 billion, increasing 5.2% from 2024. However, the compulsory insurance segment recorded an underwriting loss of approximately CNY 23 billion, indicating continuing pressure on claims expenditure and insurance profitability.
PICC Property and Casualty and other major domestic insurance groups operate across China's motor insurance industry. Compulsory liability protection represents an important part of the national market alongside voluntary vehicle damage and additional motor coverage.
Source: National Financial Regulatory Administration
Germany - Motor Insurance Premiums Increase 13.4%
Germany recorded 13.4% growth in motor insurance premium income during 2025, according to the German Insurance Association (GDV). Higher replacement parts expenses and workshop costs remained important factors influencing insurance premiums.
The association reported that replacement parts prices increased by more than 80% between 2015 and early 2026, considerably exceeding general consumer price inflation during the same period. German motor insurers returned to positive underwriting results in 2025 following several financially challenging years.
Allianz, HUK-Coburg, and other established insurers compete across Germany's substantial personal and commercial vehicle insurance market.
Source: German Insurance Association
France and Spain - Strong Premium Growth in 2025
France's automotive insurance market reached EUR 30.2 billion in 2025, increasing 7.5% annually. Individual automobile insurance contributed EUR 26.9 billion, confirming the substantial role of personal vehicle protection in national premium revenue.
Spain recorded EUR 14.285 billion in automobile insurance premiums, representing annual growth of 8.38%, according to UNESPA. Motor insurance growth exceeded the country's overall non-life insurance premium increase of 7.79%.
Both countries maintain substantial established motor insurance portfolios, with premium increases reflecting repair expenditure, claims costs, and adjustments across existing policies.
Source: France Assureurs
Source: UNESPA
Japan and South Korea - Established Automotive Insurance Markets
Japan maintains separate compulsory automobile liability and voluntary motor insurance arrangements. The General Insurance Association of Japan publishes statistics for these insurance lines, while Tokio Marine, MS&AD, and Sompo remain major participants.
Japan's established vehicle population and domestic insurance industry support substantial policy renewal activity, particularly across voluntary automobile insurance.
South Korea also has a developed motor insurance sector, with Samsung Fire & Marine, DB Insurance, Hyundai Marine & Fire, and KB Insurance among the principal providers. Direct insurance distribution, claims performance, and premium competition remain important features of the Korean market.
Source: General Insurance Association of Japan
India - Mandatory Third-Party Insurance and Growing Vehicle Protection Demand
India represents an important automotive insurance market across passenger cars, two-wheelers, commercial transportation, and corporate fleets. Third-party liability insurance is compulsory, while own-damage coverage is available separately or through combined policies.
IRDAI distinguishes motor third-party and own-damage insurance in its industry reporting, providing separate indicators of mandatory and voluntary vehicle protection.
ICICI Lombard, New India Assurance, Bajaj General Insurance, HDFC ERGO, and other private and public insurers compete across the Indian market. Automobile dealerships, intermediaries, direct insurance channels, and digital distribution remain important areas of competition.
Source: Insurance Regulatory and Development Authority of India
Brazil - One of Latin America's Largest Motor Insurance Markets
Brazil's motor insurance premiums reached BRL 28.92 billion in the first half of 2025, representing nominal growth of 5.94%, according to national insurance regulator SUSEP.
The regulator subsequently reported 6.79% nominal motor insurance premium growth for full-year 2025, alongside real growth of 1.66%. Brazil remains a substantial Latin American motor insurance market, serving passenger vehicles, commercial transportation, and business fleets.
Porto, Bradesco Seguros, and Tokio Marine are among the established insurers operating in Brazil.
Source: SUSEP - Brazilian Insurance Market Statistics
Which Companies Lead Competition in the Global Automotive Insurance Market?
The global automotive insurance industry encompasses major national motor insurers, international insurance groups, and commercial vehicle specialists. State Farm, Progressive, Berkshire Hathaway/GEICO, Allstate, Allianz, AXA, Zurich Insurance Group, Tokio Marine, PICC Property and Casualty, and ICICI Lombard are among the prominent participants.
State Farm and Progressive Lead U.S. Personal Automobile Insurance
State Farm recorded USD 69.16 billion in private passenger automobile written premiums during 2025, narrowly exceeding Progressive's USD 69.01 billion. Their respective U.S. market shares reached 18.7% and 18.6%, placing both companies substantially ahead of many competitors.
Berkshire Hathaway's GEICO and Allstate also maintain large personal automobile insurance portfolios, with market shares of 11.6% and 10.2%, respectively.
Progressive holds a stronger position in commercial automobile insurance. The company generated USD 10.18 billion in commercial motor premiums during 2025, representing 13.2% of the U.S. market. Travelers followed with USD 4.20 billion and a 5.5% share.
Source: Insurance Information Institute – Insurance Company Rankings
International Insurers Maintain Strong Regional Positions
Allianz, AXA, and Zurich are established participants in European and international automotive insurance markets. Their operations include personal motor policies, commercial fleet coverage, and insurance services distributed through agents, brokers, and direct channels.
Tokio Marine maintains a major position in Japan and international insurance markets, while PICC Property and Casualty is among China's prominent motor insurers. In India, ICICI Lombard competes with established private and public insurance providers across passenger and commercial vehicle coverage.
National regulations, underwriting results, claims expenditure, and customer retention remain important measures of competitive performance across these markets.
Primary Research Sources
- Swiss Re - Global Motor Insurance Perspective
- Insurance Information Institute - Automotive Insurance Statistics
- Insurance Information Institute - 2025 Private Passenger Insurer Rankings
- Insurance Information Institute - Commercial Auto Insurer Rankings
- J.D. Power - 2026 U.S. Auto Insurance Study
- J.D. Power - 2026 U.S. Insurance Shopping Study
- Association of British Insurers - 2025 Motor Claims
- GDV - German Insurance Industry Results 2025
- UNESPA - Spain Insurance Premium Statistics 2025
- China National Financial Regulatory Administration - Motor Liability Insurance Statistics
- SUSEP - Brazil Insurance Industry Results 2025
- IRDAI - Indian Motor Insurance Coverage