

Agriculture Tractor Market (2025-2034)
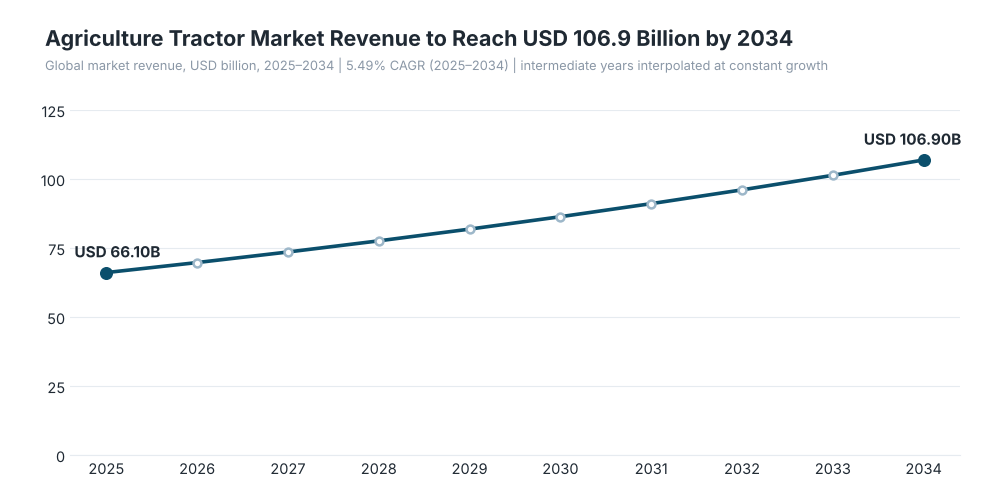
The Global Agriculture Tractor Market is estimated at USD 66.10 billion in 2025 and is projected to reach USD 106.90 billion by 2034, advancing at a CAGR of 5.49%.



Quick Enquiry
How Large Is the Agriculture Tractor Market and What Is Fueling Its Expansion?
The Global Agriculture Tractor Market is estimated at USD 66.10 billion in 2025 and is projected to reach USD 106.90 billion by 2034, advancing at a CAGR of 5.49%. This estimate is positioned between current published industry estimates and is independently modeled rather than copied from any single market-research publisher.
Agricultural tractors remain the core mechanization asset for plowing, seedbed preparation, sowing, spraying, fertilizer application, haulage and harvest support. Demand is no longer moving in one direction. India’s tractor retail sales reached 996,633 units in CY2025, up 11.52%, while Europe recorded 144,400 agricultural tractor registrations in 2024, an 8.1% decline. In the U.S., February 2026 sales fell 12.2% to 9,804 units, showing how financing costs and farm economics can delay purchases. At the same time, European registrations above 185 kW rose nearly 20%, showing a clear shift toward fewer, larger and more productive machines.
Key Report Takeaways
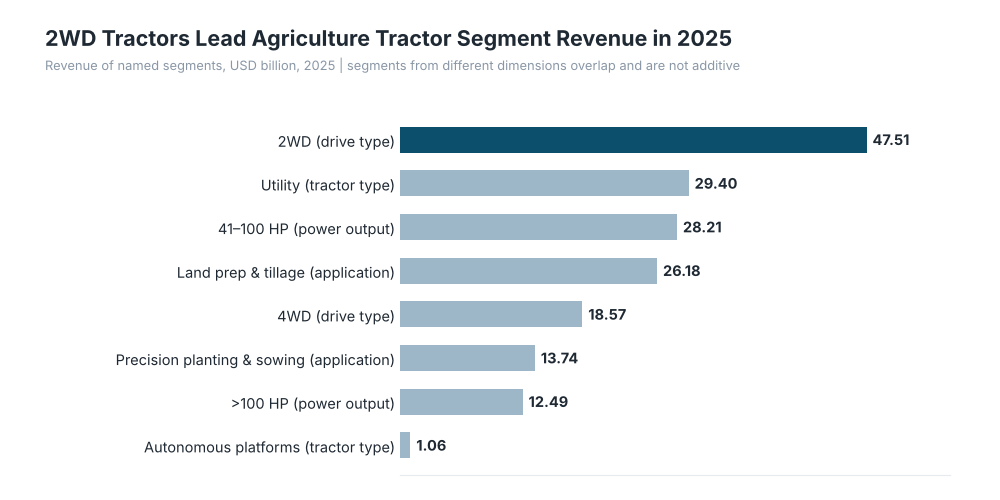
- The 41–100 HP segment remains the largest engine-power block, representing an estimated 42.7% share or approximately USD 28.21 billion in 2025, with a 5.1% CAGR as medium-duty tractors balance affordability, implement compatibility and multi-crop use.
- More than 100 HP tractors are the fastest-expanding power class, holding an estimated 18.9% share worth about USD 12.49 billion in 2025 and advancing at an estimated 8.2% CAGR as commercial farms seek higher field capacity and fewer operating hours.
- Two-wheel-drive tractors retain the largest driveline position at an estimated 71.9% share, equivalent to roughly USD 47.51 billion in 2025, growing at 4.5% CAGR through continued adoption across price-sensitive and flat-terrain farming systems.
- Four-wheel-drive tractors are gaining ground faster, with an estimated 28.1% share or USD 18.57 billion in 2025 and a 7.4% CAGR as farmers adopt heavier implements, higher-power platforms and precision-enabled machinery.
- Utility tractors account for an estimated 44.5% of 2025 market revenue, around USD 29.40 billion, expanding at 4.7% CAGR because one machine can cover tillage, transport, loader work and livestock-related duties.
- Autonomous tractor platforms remain a small base but the fastest-growing tractor type, estimated at 1.6% share or USD 1.06 billion in 2025, with a modeled 24.5% CAGR as labor availability, autonomy retrofits and remote fleet management improve.
- Land preparation and tillage represent an estimated 39.6% share of 2025 revenue, approximately USD 26.18 billion, with a 4.3% CAGR because these operations remain fundamental across virtually every cropping cycle.
- Precision planting and sowing applications hold an estimated 20.8% share, or about USD 13.74 billion in 2025, and are projected to grow at 6.6% CAGR as tractor platforms increasingly work with guidance, variable-rate and connected implement systems.
Agriculture Tractor Market Regulations and Standards Are Raising the Technology Bar
Agricultural tractor demand is increasingly influenced by emissions compliance, safety certification and type-approval requirements rather than horsepower alone. In the U.S., diesel tractor engines fall within EPA nonroad emissions regulation, making cleaner engine architectures and after-treatment systems important for new-machine development. In Europe, Regulation (EU) 2016/1628 establishes emission limits and type-approval requirements for engines used in non-road mobile machinery, including agricultural applications, while Regulation (EU) No. 167/2013 provides the broader framework for approval of agricultural and forestry vehicles.
India is entering another compliance transition through Bharat Tractor Emission standards. Government and industry documentation has linked TREM V implementation with higher equipment costs and possible pre-buying before the new requirements take effect. The Ministry of Road Transport and Highways has also issued provisions supporting type approval and conformity-of-production testing for TREM IV and V agricultural tractors using alternate or cleaner fuels. Safety requirements are complemented by BIS standards such as IS 12239 for agricultural tractor safety features, covering areas including rollover protection, braking, lighting and operator workplace provisions. ISO 25119 also governs safety-related parts of control systems used in agricultural and forestry tractors.
Agriculture Tractor Market Segmentation Is Shifting From Basic Power to Productive Power
41–100 HP tractors:
This remains the commercial center of the market, with an estimated 42.7% share worth USD 28.21 billion in 2025 and a 5.1% CAGR. The reason is straightforward. This class handles common tillage, sowing, spraying, haulage and PTO-driven work without the cost burden of a very high-power machine. India’s shift toward 41–50 HP tractors reflects rising purchasing power, commercial usage and higher irrigation intensity. The segment is also broad enough to serve fragmented farms and medium holdings. For example, John Deere offers 5D and 5E tractors across the mainstream utility range, while TAFE supports the segment through Eicher, Massey Ferguson and TAFE-branded platforms.
More than 100 HP tractors:
The high-power segment is moving faster, posting a modeled 8.2% CAGR and reaching an estimated 18.9% revenue share, or USD 12.49 billion, in 2025. Large farms increasingly value work rate over minimum purchase cost. Europe demonstrates the change clearly: tractor registrations above 185 kW increased by nearly 20% in 2024 despite the broader market falling. For example, CLAAS is expanding its premium AXION portfolio into the 330–450 HP range, while New Holland’s T8 family serves high-horsepower row-crop operations with connectivity and precision-farming capabilities.
Agriculture Tractor Market Driveline Economics Are Opening Space for 4WD
2WD tractors:
Two-wheel-drive tractors account for an estimated 71.9% of global revenue, about USD 47.51 billion in 2025, with a 4.5% CAGR. Their strength comes from lower purchase prices, simpler maintenance and suitability for flat agricultural areas where maximum traction is not always necessary. The supplied market evidence also shows how strongly this configuration fits India's volume-led model, where affordability remains a central procurement criterion.
4WD tractors:
Four-wheel-drive models are estimated at 28.1% share and USD 18.57 billion in 2025, but are growing at 7.4% CAGR. Traction becomes critical when farms use heavier implements, operate on wet or uneven soils, or move toward higher horsepower. In India, 4WD penetration has risen as customers move toward more demanding applications and larger machines. For example, Mahindra’s OJA platform makes 4WD standard across its lightweight global tractor architecture, while John Deere provides 2WD and 4WD alternatives across its 5E range.
Agriculture Tractor Market Product Mix Is Expanding Beyond Traditional Utility Machines
Utility tractors:
Utility tractors are estimated to command 44.5% of 2025 global revenue, around USD 29.40 billion, and grow at 4.7% CAGR. Their advantage is flexibility. A single platform can support field preparation, transport, loaders, livestock work and municipal tasks, which makes them especially attractive when farmers are unwilling to maintain separate machines for every operation. For example, Kubota’s Standard L and MX families cover compact and utility requirements with multiple configurations, while TAFE positions Eicher and Massey Ferguson tractors around broad agricultural and commercial use.
Autonomous tractor platforms:
Autonomous platforms represent only about 1.6% of revenue today, estimated at USD 1.06 billion, but the modeled CAGR is 24.5%. The important change is that autonomy is moving from demonstration technology toward retrofit systems and commercially available machines. Labor shortages and the need to run equipment for longer operating windows are making remote control, machine perception and autonomous task planning more practical. For example, AgXeed combines autonomous AgBots with its TraXwise planning platform and vehicle control units, while Sabanto converts existing tractors into remotely managed autonomous machines, reducing the need to replace a complete fleet.
Agriculture Tractor Market Applications Are Moving Toward Higher-Value Field Operations
Land preparation and tillage:
The largest application area is estimated to represent 39.6% of market revenue, approximately USD 26.18 billion in 2025, with a 4.3% CAGR. Tillage remains difficult to displace because it demands high drawbar power and repeated field passes, making tractors indispensable for plowing, cultivation and soil preparation. Demand remains strongest where mechanization is still expanding, particularly in Asia, while mature regions increasingly focus on reducing the number of passes and increasing work width.
Precision planting and sowing:
Precision planting and sowing are estimated at 20.8% share or USD 13.74 billion in 2025 and are growing at 6.6% CAGR. The attraction is not simply faster planting. Guidance, machine control and connected implements can improve pass consistency and reduce overlap, making tractor technology directly relevant to input efficiency. For example, Case IH integrates connectivity and precision capabilities into its Magnum platform, while CLAAS is pushing automated drivetrain management, digital connectivity and assistance systems into its new large-tractor generations.
Agriculture Tractor Market Regional Demand Is Becoming Increasingly Bifurcated
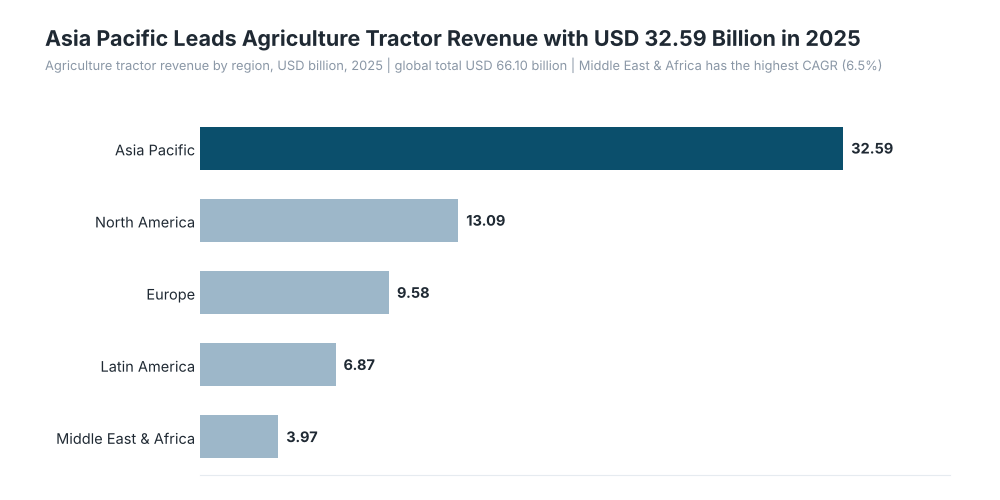
Asia Pacific is estimated to remain the dominant region with a 49.3% share, equivalent to approximately USD 32.59 billion in 2025, and a 6.1% CAGR through 2034. India is the central volume engine. Retail tractor sales reached 996,633 units in 2025 and increased 11.52%, supported by mechanization, rural demand and financing-led access. Demand is increasing not because farms are suddenly becoming larger, but because mechanization is still spreading across fragmented holdings and rental-based farming services. For example, Mahindra is extending lightweight 4WD coverage through OJA, while TAFE uses Massey Ferguson, Eicher and TAFE brands across a broad domestic and export portfolio. Escorts Kubota is also reinforcing the volume market through Powertrac models ranging from sub-compact to higher utility applications.
North America holds an estimated 19.8% share, around USD 13.09 billion in 2025, with a 4.3% CAGR. Growth here is more replacement-driven than first-time mechanization. The short-term picture is uneven: U.S. tractor sales dropped 12.2% in February 2026, with 100+ HP units declining 25.8%, while four-wheel-drive tractors were the only category showing growth that month. Demand is therefore shifting toward machines that justify the capital outlay through greater output, connectivity and reduced operator workload. For example, John Deere markets compact, utility and row-crop/4WD tractors across a broad portfolio, while Case IH is integrating connectivity and precision-farming functionality into high-horsepower Magnum tractors.
Europe is projected to represent about 14.5% of global revenue, or USD 9.58 billion in 2025, with a 3.2% CAGR. Unit demand is under pressure from high financing costs, weak farm economics and expensive equipment, with agricultural tractor registrations reaching a 10-year low of 144,400 units in 2024. Yet the decline conceals a premiumization trend. Tractors above 185 kW rose nearly 20%, while France recorded a 13% increase in registrations above 300 HP. For example, CLAAS is extending large AXION machines to 450 HP, while SDF continues developing high-output DEUTZ-FAHR and SAME platforms alongside digital and autonomous agricultural technologies.
Latin America is estimated at 10.4% share, approximately USD 6.87 billion in 2025, and a 4.8% CAGR. Brazil remains the anchor market, although recent demand has normalized rather than collapsed. Tractor sales reached 42,300 units in 2025, down 3.4% from the previous year and remaining close to the region's longer-term market baseline. Agricultural exports, large-scale crop production and continued fleet modernization should keep replacement demand active. For example, CNH serves the region through Case IH and New Holland Agriculture, while AGCO supports commercial farms through Fendt, Massey Ferguson and Valtra product lines.
The Middle East and Africa region is modeled at 6.0% share, about USD 3.97 billion in 2025, with a 6.5% CAGR. Demand is smaller but increasingly linked to commercial farming, food-security investment, irrigation development and mechanization programs. Buyers generally favor robust machines that are easier to maintain and can handle varied terrain and crop systems. For example, TAFE exports tractors across Africa with utility-focused configurations, while ZETOR serves international markets with Proxima, Forterra, Crystal and other agricultural tractor lines.
Agriculture Tractor Market Competition Is Being Reshaped by Power, Connectivity and Local Manufacturing
The competitive landscape is no longer defined only by the number of tractors sold. Manufacturers are defending their position through localized manufacturing, dealer density, financing, specialty models, high-horsepower machines, digital platforms and autonomy. The principal competitive universe screened for this analysis includes Mahindra, John Deere, CNH Industrial, AGCO, Kubota, TAFE, Escorts Kubota, Sonalika, SDF, CLAAS, Argo Tractors, Yanmar, LS Tractor, TYM, ZETOR, VST, Captain Tractors, Indo Farm, Preet and emerging autonomy specialists such as AgXeed and Sabanto. Company portfolios vary substantially by market, and that variation is becoming a competitive advantage rather than a complication.
Mahindra & Mahindra: Mahindra competes across lightweight, compact, utility and higher-power tractors, with OJA extending its 4WD offering from sub-compact to large-utility platforms. The group combines broad tractor manufacturing scale with region-specific products and an extensive distribution base.
John Deere: John Deere spans compact tractors, utility tractors, row-crop and four-wheel-drive machines, as well as high-value crop and specialty tractors. Its Indian portfolio includes 5D, 5E, 5M and specialty platforms, while its wider range extends into very high-horsepower 8 and 9 series equipment.
CNH Industrial: CNH serves the tractor market primarily through Case IH, New Holland Agriculture and STEYR, combining conventional tractor ranges with precision-agriculture technology and equipment ecosystems.
AGCO Corporation: AGCO operates through Fendt, Massey Ferguson and Valtra tractor brands, covering tracked, wheeled, specialty, utility and high-performance applications while also linking tractors with precision agriculture and autonomous solutions.
Kubota Corporation: Kubota maintains a strong presence in compact and utility tractors, with the Standard L and MX families addressing lower and mid-horsepower applications and broader agricultural platforms supporting commercial users.
TAFE: TAFE combines TAFE, Eicher, Massey Ferguson and IMT tractor brands, providing compact, utility and higher-power machines across India and export markets. Its portfolio is especially relevant to price-sensitive and mixed-farming markets.
Escorts Kubota: The company serves the Indian market through tractor families including Powertrac, with offerings spanning compact, utility and higher-output machines. Its Powertrac range covers approximately 11 to 60 HP categories across multiple series.
Sonalika Group: Sonalika provides a broad 20–120 HP tractor portfolio with standard, heavy-duty and specialty-oriented configurations, positioning the brand strongly in export and emerging agricultural markets.
SDF Group: SDF's agricultural portfolio is sold under SAME, DEUTZ-FAHR, Hürlimann, Grégoire and VitiBot, spanning conventional tractors, specialized machines, harvesters and autonomous agricultural platforms.
CLAAS: CLAAS is building its tractor position around premium mid- and high-horsepower machines. Its latest ARION 6, AXION 8 and AXION 9 families bring together heavy-duty field capability, CVT transmissions, automation and digital connectivity, extending up to 450 HP.
Argo Tractors: Argo manufactures tractors under Landini and McCormick, with a portfolio that includes specialized, utility and higher-performance machines for different agricultural environments.
ZETOR: ZETOR continues to compete through the COMPAX, MAJOR, PROXIMA, FORTERRA, CRYSTAL and newer Series 5 and Series 6 families, balancing robustness and cost with broader international applications.
LS Tractor and TYM: LS Tractor competes across sub-compact, compact and utility tractors, while TYM provides a similarly broad progression from sub-compact machines to utility tractors, including newer higher-power platforms.
AgXeed and Sabanto: The emerging autonomy layer is increasingly important. AgXeed develops autonomous AgBots alongside planning, vehicle-control and implement-control technologies, whereas Sabanto focuses on retrofitting existing tractors with autonomy systems, allowing farmers to automate field work without replacing the underlying machine.
The competitive implication is clear. Volume leadership will continue to matter in markets such as India, but premiumization, precision systems, autonomy and lower-cost retrofit models are creating new profit pools. The supplied evidence already shows this split: Mahindra and Swaraj sold 424,509 tractors in India in 2025, while higher-power demand was strengthening in mature Western markets. Meanwhile, the used-equipment market is becoming a genuine competitive pressure; Italy recorded more than 57,000 used tractor sales in 2024 against roughly 15,400 new registrations.
The market therefore is not simply expanding. It is changing shape. Emerging economies are adding tractor volume, mature markets are concentrating spending on higher-productivity equipment, and technology-focused entrants are attacking the operator and software layer of the machine. That is where the next phase of Agriculture Tractor Market value creation is likely to occur.